North Carolina Home Loans

Your North Carolina
Mortgage, Handled.

Every one of the 100 counties shares the same $832,750 loan limit, so the limit is never what decides your purchase here. What decides it is the assistance, which is forgivable but not for eleven years, and a reappraisal cycle that can move your tax bill overnight.

Estimate your payment
What will it cost
per month?
$
%
%
%
$0/mo
 
Illustration only, not a rate quote or an offer of credit. 30 year fixed. North Carolina appraises property at its true value in money and each county sets its own rate, so there is no single statewide figure. Type your county rate over the estimate. Insurance, HOA dues and mortgage insurance are not included.
$1.5B+
Loans Funded
34+
Years Experience
100
Counties Served
7
States Licensed
Where We Lend

Lending Across North Carolina

We lend in all 100 counties. These are the markets our clients move to most, whether that is a relocation, a return home, or a second property.
Mecklenburg County
Mecklenburg County
Charlotte · Huntersville · Matthews · Davidson
$832,750
2026 limit

The largest housing market in the state and the one where our clients most often land on a corporate relocation.
Wake County
Wake County
Raleigh · Cary · Apex · Wake Forest
$832,750
2026 limit

Research Triangle employment, heavy new construction, and the county where builder incentives come up in almost every conversation.
Durham County
Durham County
Durham · Research Triangle Park
$832,750
2026 limit

Older housing stock beside new build, which is where renovation financing and appraisal condition start to matter.
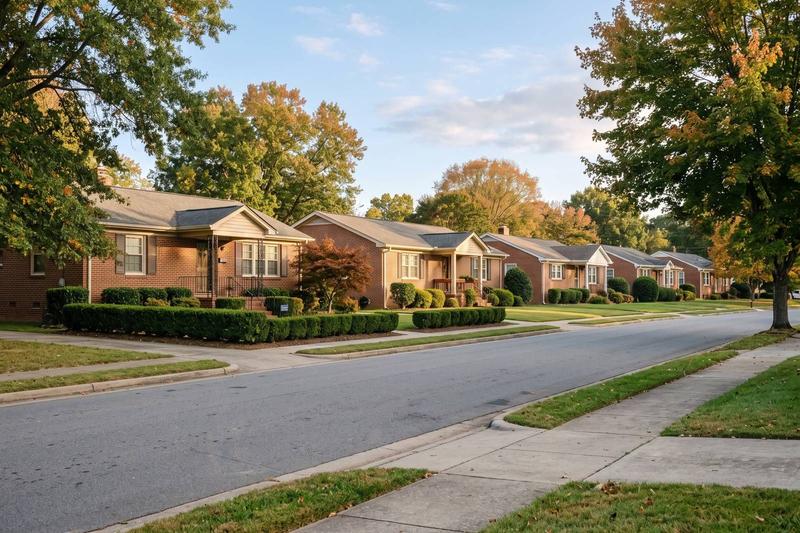
Guilford County
Guilford County
Greensboro · High Point · Jamestown
$832,750
2026 limit

One of the more affordable metros in the state, and the part of North Carolina where the NCHFA assistance still covers a meaningful share of the down payment.
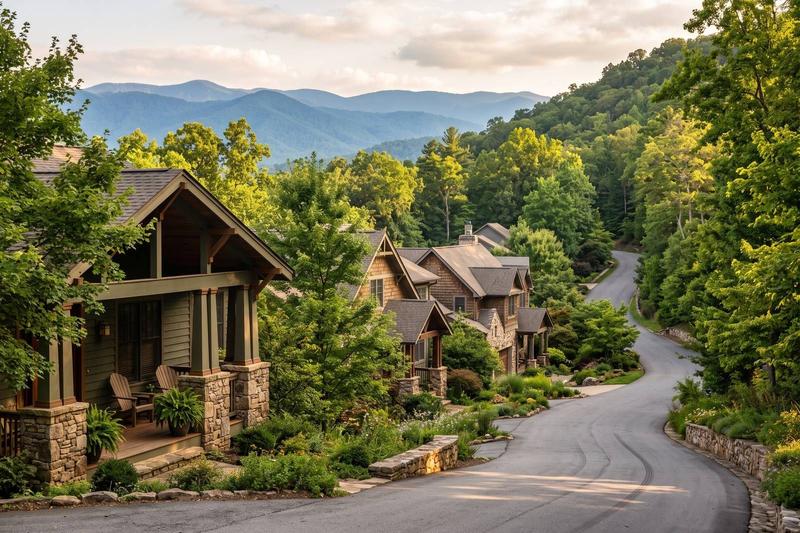
Buncombe County
Buncombe County
Asheville · Black Mountain · Weaverville
$832,750
2026 limit

Mountain market with a strong second home and short term rental component, so occupancy and insurance questions come early.
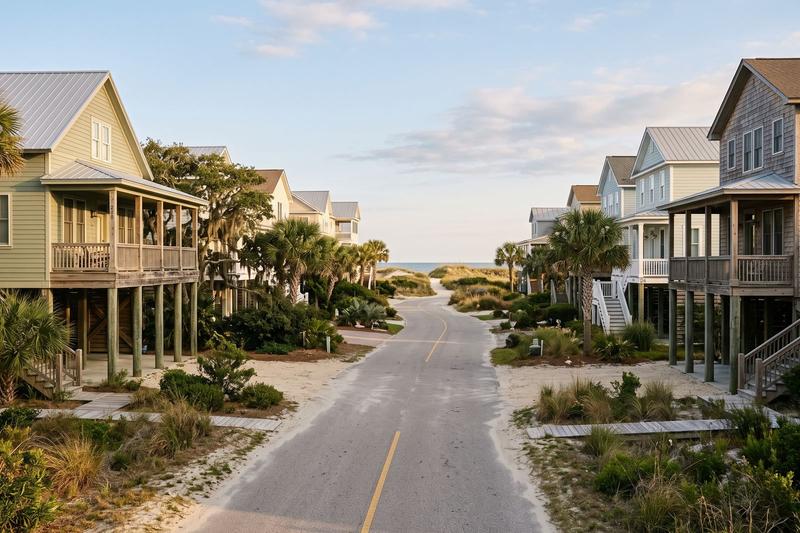
New Hanover County
New Hanover County
Wilmington · Wrightsville Beach · Carolina Beach
$832,750
2026 limit

Coastal, which means wind and flood coverage shape the payment as much as the rate does.

Buying somewhere else in North Carolina? The loan limit is identical in all 100 counties, so the conversation moves straight to assistance eligibility, the county tax rate, and insurance.

Call or text
Assistance Programs

Help That Is Forgivable, Eventually

The North Carolina Housing Finance Agency runs the state assistance, and its terms are unusually generous on income and unusually long on forgiveness.

Quick Answer

Nothing is forgiven before year eleven. Both NCHFA products forgive at 20% a year across years 11 through 15. Sell or refinance in year ten and the full balance is still owed. That is not a reason to avoid them, it is a reason to know your timeline before you take one.

Maximum
$15,000
NC 1st Home Advantage Down Payment
0% deferred second mortgage.

The larger of the two. A flat $15,000 rather than a percentage, which is why it goes furthest in the more affordable metros.

$15,000, not a percentage
0% interest, no monthly payment
Forgiven 20% a year across years 11 to 15
First time buyers, veterans, or targeted census tracts
Assistance
Up to 3%
NC Home Advantage Mortgage
First time and move up buyers.

The agency’s main program. Assistance is calculated as a percentage of the loan amount, so it scales with the purchase rather than being capped at a flat figure.

Up to 3% of the loan amount
Same 11 to 15 year forgiveness schedule
No first time buyer requirement
Occupy as your primary residence within 60 days
Income cap
$158,000
The eligibility that surprises people
Generous by any standard.

The NCHFA income limit is high enough that a lot of buyers who assume they earn too much for state assistance actually qualify. It is worth checking rather than assuming.

$158,000 annual income limit
Credit score 640, or 660 for manufactured homes
Sales price follows your loan type rather than an NCHFA figure
Available through participating lenders

Program terms from the North Carolina Housing Finance Agency, verified September 2026. NCHFA sales price limits follow the underlying loan type rather than a single agency figure, so none is quoted here. Confirm current terms with the agency or with us before you rely on them.

Loan Programs

Every Mortgage Option, One Team

The 2026 conforming limit is $832,750 in every North Carolina county. Which program fits comes down to your down payment, your credit and the condition of the property.

Conventional
3% down for first time buyers

The default for most North Carolina purchases, and the loan type NCHFA assistance most often sits behind.

2026 limit: $832,750Statewide, no high cost county3% down available
VA Loans
No down payment, no monthly mortgage insurance

North Carolina has one of the largest veteran populations in the country and a heavy active duty presence. With full entitlement there is no loan limit.

0% downNo monthly MINo limit with full entitlement
FHA
3.5% down, more forgiving on credit

Useful where the housing stock is older or the credit file is still being rebuilt. FHA sets its own county limits on a separate table from the conforming one.

3.5% downLower credit thresholdsOwn county limit table
Renovation
Buy it and fix it on one loan

Common in Durham and the older Greensboro and Winston-Salem neighborhoods, where the price is in the location and the work is in the house.

One closingRepairs financedOlder stock friendly
Jumbo
Above $832,750

Above the conforming limit the underwriting standards change, and in Charlotte and the Triangle that threshold comes up more often than the state average suggests.

Above $832,750Reserves requiredTighter documentation
Refinance
Rate, term or cash out

Worth a look after a reappraisal year, when a higher assessed value can change what a cash out refinance will support.

Rate and termCash outFree review
Not sure which one fits?

Send us the county, the price and your down payment and we will tell you which programs are open to you before you write an offer.

Get pre-approved
Closing Costs

The Excise Tax the Seller Pays

North Carolina charges one of the lowest transfer taxes in the country, and the statute puts it on the seller rather than the buyer. That is the opposite of what our DC and Maryland clients expect.

Purchase priceState excise tax at $1.00 per $500Who the statute billsWhat the same price costs a DC buyer
$300,000$600The seller$3,300 to $6,600 combined
$450,000$900The seller$9,900 to $13,050 combined
$600,000$1,200The seller$13,200 to $17,400 combined
$832,750$1,666The seller$18,321 to $24,150 combined

North Carolina rate from General Statute 105-228.30, which sets the excise tax at one dollar on each five hundred dollars or fractional part and states that the transferor pays it. The DC column is the combined buyer recordation and seller transfer tax at the rates on our Washington DC page and is shown for scale only. Who actually pays any of these is ultimately set by your contract.

VA Loans in North Carolina

Serving Those Who Serve

North Carolina carries one of the largest military and veteran populations in the country, from the coastal bases to the Triangle and Charlotte veteran communities.

No down payment with full entitlement
No monthly mortgage insurance, ever
No loan limit with full entitlement, anywhere in the state
The funding fee is waived for veterans receiving compensation for a service connected disability
Check your VA eligibility
Fort Bragg
US Army
Cumberland and Hoke counties
Popular nearby areas: Fayetteville, Spring Lake, Hope Mills
Camp Lejeune
US Marine Corps
Onslow County
Popular nearby areas: Jacksonville, Swansboro, Richlands
Seymour Johnson Air Force Base
US Air Force
Wayne County
Popular nearby areas: Goldsboro, Pikeville

VA loan entitlement rules from VA.gov. Funding fee exemptions depend on service history and disability status. Installation locations are given for orientation only and are not endorsements.

Common Questions

North Carolina Mortgage Questions, Answered

What buyers relocating to North Carolina ask us most.

What is the conforming loan limit in North Carolina for 2026?
It is $832,750, and unlike Virginia, Maryland or West Virginia the figure does not change anywhere in the state. All 100 counties sit at the national baseline, so there is no high cost county and no county line worth chasing for a higher limit.
Do you have to pay back NCHFA down payment assistance?
Yes, but not quickly. Both the $15,000 NC 1st Home Advantage Down Payment and the up to 3% NC Home Advantage assistance forgive at 20% a year across years 11 through 15, reaching full forgiveness at the end of year 15. Before year 11 nothing has been forgiven, so a sale or a refinance in year ten means repaying the whole amount.
What are the NCHFA income limits in North Carolina?
Probably not. The NC Home Advantage income limit is $158,000, which is high enough that most buyers who assume they are over it are not. It costs nothing to check, and the program has no first time buyer requirement.
Who pays the transfer tax in North Carolina?
The statute puts it on the seller. General Statute 105-228.30 sets the excise tax at one dollar per five hundred dollars of value and says the transferor pays it. At $450,000 that is $900. Buyers coming from DC or Maryland are usually surprised by how small it is and by which side of the table it lands on.
Why did my North Carolina property tax go up after revaluation?
You were probably in a reappraisal year. North Carolina appraises property at its true value in money and counties reappraise at least every eight years, with some choosing shorter cycles and larger counties required to move sooner when their sales assessment ratios drift. Between reappraisals your assessed value can sit well below the market, then catch up all at once.
What credit score do I need for the NC Home Advantage Mortgage?
A 640 minimum for NC Home Advantage, or 660 for a manufactured home. That is a floor for the program, not a promise of approval, and the rest of the file still has to work.
Can you lend on a second home or a short term rental in Asheville or Wilmington?
Yes, though the terms differ from a primary residence and the insurance is often the part that moves the payment most, particularly on the coast. Tell us the intended use up front, because it changes the loan program and the down payment before it changes anything else.
I am buying in North Carolina and selling in Virginia, Maryland or DC. Can you handle both?
That is the usual shape of a relocation. The financing runs through the Ken Byrne Team at ALCOVA Mortgage and the listing through the Jamil Brothers Realty Team, and the two sides coordinate the timing so you are not carrying both properties.
Still have a question?

Send us the county and the price point and we will give you the real numbers rather than a range.

Call (571) 621-5413
Two Teams. One Purpose.

Selling Your North Carolina Home Too?

Buying in North Carolina usually means selling something first. The Jamil Brothers Realty Team offers full service listings from 1.5%. The listing side is handled by the realty team and the financing by the Ken Byrne Team at ALCOVA Mortgage, and that is what makes a simultaneous sale and purchase easier to time.

What full service includes

Listings from 1.5%

Full MLS syndication
Your listing reaches every major portal buyers actually search.
Professional photography
Included, not an upsell, because listing photos drive the showings.
Negotiation and closing
A licensed agent with you from offer through settlement.

Listing services are provided by the Jamil Brothers Realty Team. Mortgage financing is provided by the Ken Byrne Team at ALCOVA Mortgage. The two are separate businesses working the same transaction.

Get Started

Your North Carolina Mortgage
Starts Here

Send us the county and the price point. We will tell you whether the state assistance is worth taking given how long you plan to stay, and what the county tax rate does to the payment.

Call or Text (571) 621-5413

Also buying or selling in Virginia, Maryland or DC? We are licensed across the region and the numbers change at every state line.

See our Virginia page

This page is general information, not a commitment to lend or an offer of credit. Program rules, loan limits, assistance amounts and tax rates change, and several programs described here open and close with funding. Verify current figures with the issuing agency before relying on them. Loans originated by Ken Byrne, NMLS ID# 187129, ALCOVA Mortgage LLC, NMLS ID# 40508. Licensed in VA, DC, MD, NC, SC, FL & WV.

Equal Housing Lender