Your DC
Mortgage, Handled.
One loan limit covers the whole District, which makes DC simpler than Maryland or Virginia. The complications are the recordation tax that jumps at $400,000 and an assistance program that is awarded by lottery.
per month?
Lending Across the District
The loan limit and the tax rate are the same in every ward. What changes is the housing stock, and that is what changes your loan.
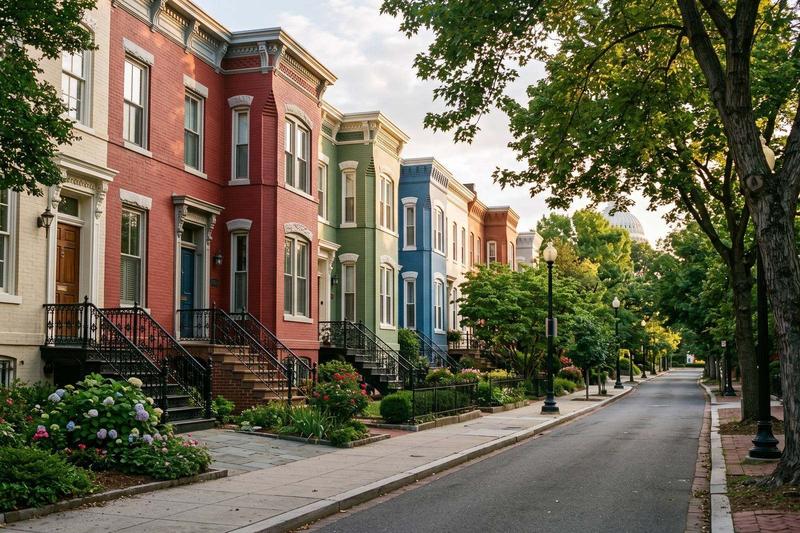
Federal era rowhouses, many of them historic, where renovation financing comes up more often than anywhere else in the city.
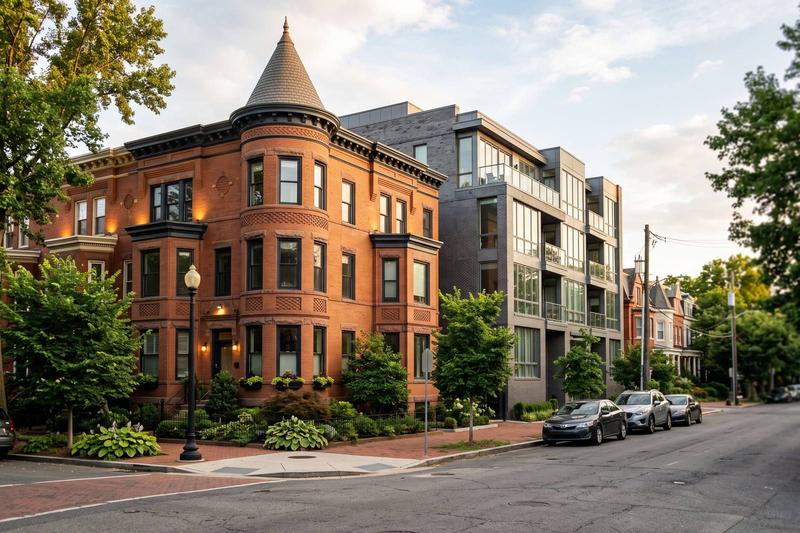
Rowhouse conversions and new condos side by side, so the condo project review usually matters more than the borrower does.
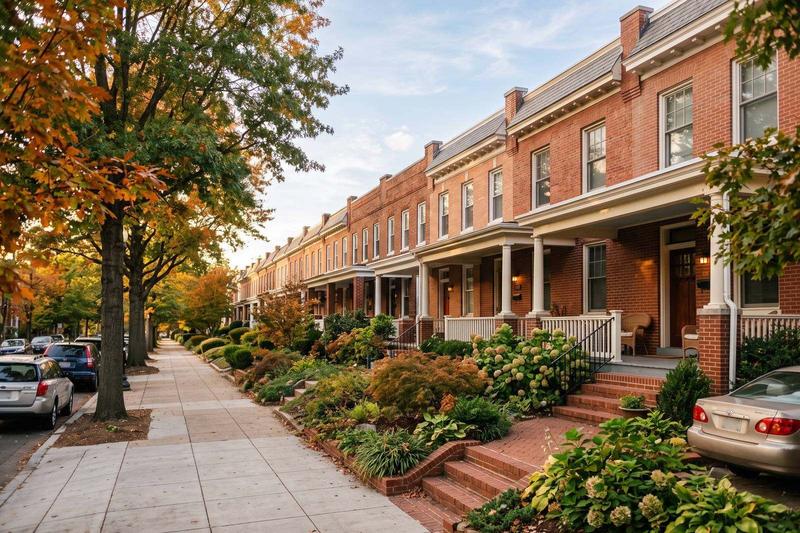
The part of the city where a purchase still lands under $400,000 often enough for the lower recordation rate to be worth chasing.
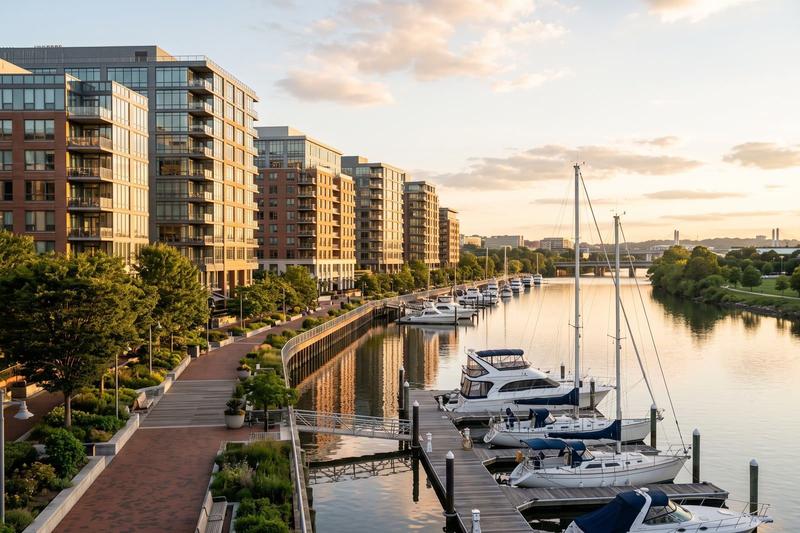
Almost entirely newer condo buildings, which means HOA dues and project approval drive what you qualify for.
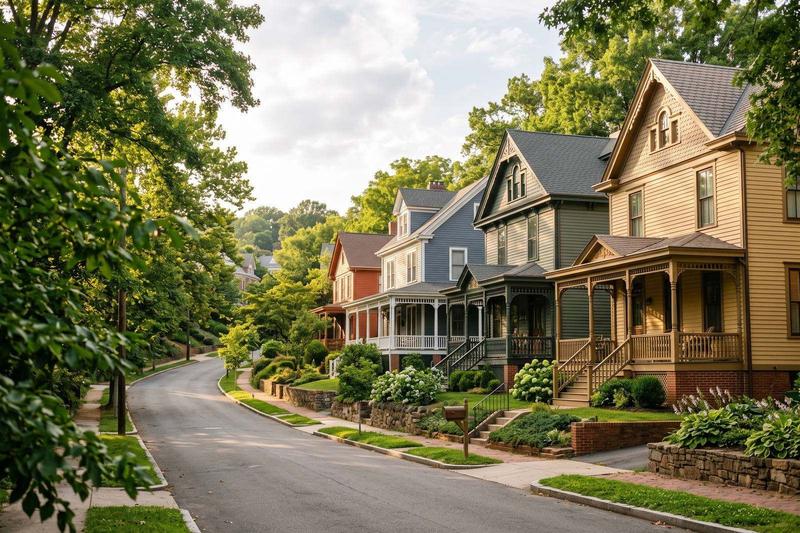
Where District assistance programs do the most work, and where HPAP files most often come together.
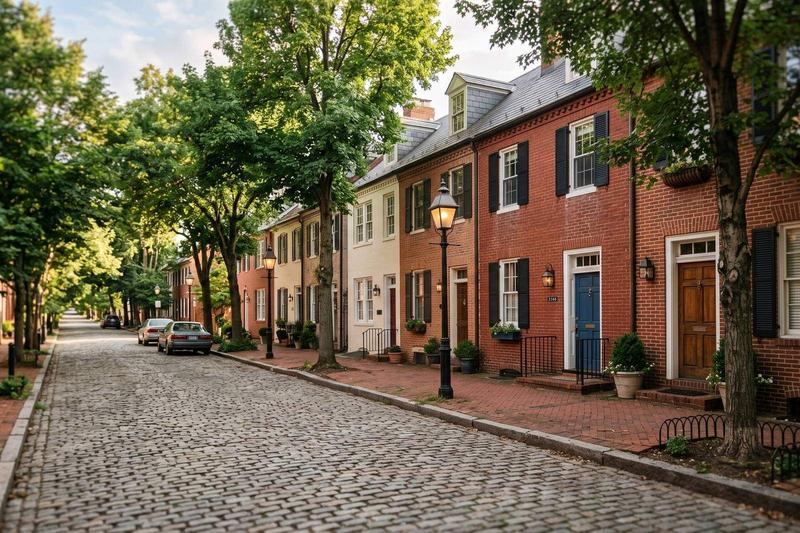
Consistently above the $1,249,125 limit, so these are jumbo conversations from the first call.
Not sure which part of the District fits your budget? We will tell you where your number actually reaches, and where it does not.
Call (571) 621-5413 and we will walk you through itDistrict Programs That Reduce Your Costs
The District has the largest down payment assistance award in the region and the hardest one to get. Knowing which of these you can actually plan around is the whole exercise.
The District will lend a qualified buyer up to $202,000 toward a down payment. The catch is that HPAP is awarded by an annual lottery, not by application order, so it is not something you can schedule a purchase around. DC Open Doors has no lottery, no sales price cap and no first time buyer requirement, which is why most of our District files use it.
The District’s flagship program. Closing cost assistance is separate and capped at $4,000. Very low and low income households make no monthly payments at all. Moderate income households defer for five years, then begin principal only payments in year six, amortised over 40 years.
A second trust covering the full required minimum down payment. It is deferred, non amortising and carries no monthly payment. It becomes due when you sell, refinance, stop using the home as your principal residence, or after 30 years.
A $20,000 deferred loan for full time District employees with at least a year of service. The service requirement is waived for police, corrections officers, firefighters, EMTs, paramedics and public or public charter school teachers, who can also qualify for additional grant assistance against a five year service agreement.
Qualified first time District buyers pay recordation tax at 0.725% instead of the standard rate. On a $500,000 purchase that is the difference between roughly $7,250 and $3,625 due at the table.
Most District files use Open Doors
HPAP is the bigger number and it is worth entering the lottery for. But you cannot build a purchase timeline around a once a year draw. Open Doors covers your minimum down payment with no monthly payment, no sales price cap and no first time buyer requirement, which means it works on a contract that is already ratified. We will tell you honestly which one your situation supports.
Talk Through BothDC DHCD and DCHFA program terms as verified in September 2026. HPAP lottery timing, income tables and the first time buyer tax ceilings change annually. Confirm current terms with the agency or call us at (571) 621-5413. This is not a commitment to lend.
Crossing into Northern Virginia instead? VHDA and Virginia Housing assistance run on their own income caps, and Virginia does not charge the recordation tax the way the District does.
Every Mortgage Option, One Team
The District sits entirely inside the high cost area, so one limit applies from Georgetown to Congress Heights.
As little as 3% down with mortgage insurance that cancels by law at 78% of original value. The 2026 baseline is $832,750, and every address in the District carries the $1,249,125 high cost ceiling.
Joint Base Anacostia Bolling sits inside the District and the federal workforce brings a large veteran population with it. Zero down, no monthly mortgage insurance, and no loan limit at all for a buyer with full entitlement.
Down to 3.5% with a 580 credit score, and more forgiving on debt to income than conventional. The FHA ceiling in the District is $1,249,125, the same as the conforming ceiling.
Anything above $1,249,125 is a jumbo. In Georgetown, Kalorama and much of Upper Northwest that is the normal case rather than the exception, so we underwrite these every week.
Much of the District’s rowhouse stock predates 1940. A renovation loan finances the purchase and the work on one loan, based on the value after improvements rather than as it stands.
Rate and term, cash out, and the VA streamline. Whether it pays depends on how long you will hold the home against what the refinance costs, and DC recordation tax is part of that maths.
Tell us the price point and your credit profile and we will tell you what actually works, including what it costs at the closing table.
Get Pre-ApprovedThe $400,000 Line
DC recordation tax is not tiered. Cross $400,000 and the higher rate applies to the whole purchase price, not just the part above the line. It is the single most expensive detail in a District contract, and the one buyers find out about last.
| Purchase price | Buyer recordation | Seller transfer | Combined | First time buyer rate |
|---|---|---|---|---|
| $399,000 | 1.1%, $4,389 | 1.1%, $4,389 | $8,778 | 0.725%, $2,893 |
| $425,000 | 1.45%, $6,163 | 1.45%, $6,163 | $12,325 | 0.725%, $3,081 |
| $500,000 | 1.45%, $7,250 | 1.45%, $7,250 | $14,500 | 0.725%, $3,625 |
| $750,000 | 1.45%, $10,875 | 1.45%, $10,875 | $21,750 | 0.725%, $5,438 |
| $1,000,000 | 1.45%, $14,500 | 1.45%, $14,500 | $29,000 | Over the ceiling |
Rates from the DC Office of the Chief Financial Officer: 1.1% of consideration for residential transfers under $400,000 and 1.45% of the entire amount above $400,000, applied to both deed recordation and deed transfer. Recordation is customarily paid by the buyer and transfer by the seller, but that is negotiable and the contract governs. The first time buyer reduced recordation rate of 0.725% carries a purchase price ceiling and income ceilings that reset each October. Figures are rounded and are an illustration, not a quote.
Serving Those Who Serve Our Country
Joint Base Anacostia Bolling sits inside the District, and the federal workforce around it means a large share of our DC files involve either VA entitlement or a District government employee. Both come with benefits most lenders handle occasionally and we handle constantly.
VA loan benefits are set by the Department of Veterans Affairs. Entitlement, funding fee and eligibility depend on service history. EAHP is a DC DHCD program for District government employees.
Washington DC Mortgage Questions
The questions District buyers ask us most.
Our team answers District mortgage questions every day, with no pressure and no obligation.
Call (571) 621-5413Selling Your DC Home Too?
Buying in the District usually means selling something first. The Jamil Brothers Realty Team offers full service listings from 1.5%. The listing side is handled by the realty team and the financing by the Ken Byrne Team at ALCOVA Mortgage, and that is what makes a simultaneous sale and purchase easier to time.
Listings from 1.5%
Listing services are provided by the Jamil Brothers Realty Team. Mortgage financing is provided by the Ken Byrne Team at ALCOVA Mortgage. The two are separate businesses working the same transaction.
We are a Washington DC mortgage lender licensed across the region, so a search that spans the District, Maryland and Virginia stays with one team.