
DSCR Loan Requirements in Virginia: 2026 Guide for Northern Virginia Investors
A DSCR loan asks one question: does the rent cover the payment?
Short answer: a DSCR loan qualifies a rental property on its rent, not on your personal income. The ratio is monthly rent divided by the full monthly payment. Published programs vary on the ratio: one requires above 1.00 and several accept less. They commonly ask for 20 to 25 percent down and a credit score of 620 to 680 or higher. In Northern Virginia the hard part is the ratio. At typical county values, 25 percent down and a 7.28 percent rate, typical rents produce a ratio of about 0.52 to 0.62.
By Ken Byrne, NMLS #187129 · ALCOVA Mortgage LLC, NMLS #40508 · Updated October 2026
This guide covers DSCR loan requirements, the math on real Northern Virginia values and rents, and the local rules investors run into. Lender terms shown are published examples read in October 2026.
To run the numbers on a specific property, talk to Ken Byrne at JB Financing.
What is a DSCR loan?
A DSCR loan is a mortgage for an investment property that is approved on the property’s rental income. DSCR stands for debt service coverage ratio.
ALCOVA Mortgage lists a DSCR loan among its loan options. Its page describes it this way:
| Feature | What ALCOVA’s DSCR page says |
|---|---|
| Qualification | Based on property income, not personal income |
| Income documents | No W-2s or tax returns required in many cases |
| Down payment | Typically 20% to 25% or more |
| Property use | Investment properties only, not a primary residence |
| Rates | May be higher than traditional loan options |
| Reserves | Requirements may apply |
Source: ALCOVA Mortgage, DSCR Loan product page, read October 6, 2026. Exact terms depend on the loan scenario; ask for current requirements.
Self-employed and need a loan for your own home instead? See our guide to bank statement loans.
How do you calculate DSCR?
Divide the monthly rent by the monthly payment. The payment includes principal, interest, taxes, insurance and any association dues, known as PITIA.
| Monthly rent | Monthly PITIA | DSCR | What it means |
|---|---|---|---|
| $3,000 | $2,400 | 1.25 | Rent covers the payment with 25% to spare |
| $3,000 | $3,000 | 1.00 | Rent exactly covers the payment |
| $2,400 | $3,000 | 0.80 | You cover a shortfall from other funds |
Formula as published in DSCR lender program guides read in October 2026.
The rent usually comes from the appraiser. The appraiser completes a rent schedule that compares the home with nearby rentals.
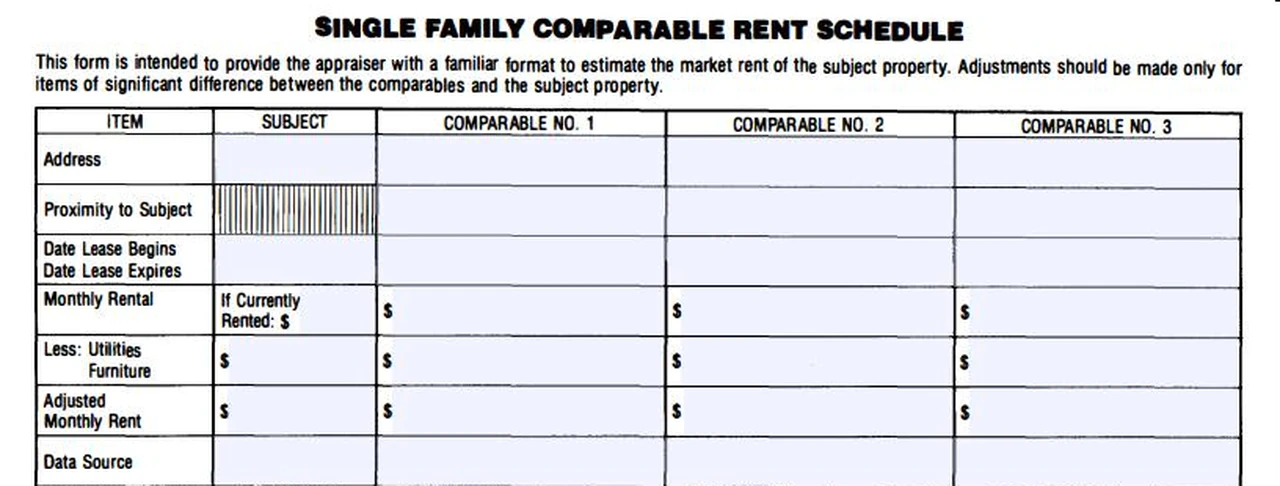
Form 1007 is the rent schedule an appraiser uses to estimate market rent. Source: Fannie Mae.
What are DSCR loan requirements in 2026?
Requirements vary by lender. Most published programs set a minimum ratio, a minimum credit score, a maximum loan-to-value and a reserve requirement.
| Requirement | Range in published programs | Examples |
|---|---|---|
| Minimum DSCR | Above 1.00 at one lender; below 1.00 accepted at several | One program requires above 1.00. Another advertises as low as 0.80. A third allows below 1.00 with a 680 score |
| Minimum credit score | 620 to 680 | One lender cites 620 generally. Two others publish 680 |
| Maximum loan-to-value, purchase | 80% at most lenders | One program goes to 85% with a 720 score |
| Maximum loan-to-value, cash-out | 75% where stated | Two programs publish 75% |
| Loan amount | $100,000 minimum is common | Published maximums run from $1 million to $4.5 million |
| Reserves | 3 to 12 months of payments | One program: 3, 6 or 12 months by loan size. Another: 6 months |
| Income documents | No tax returns or W-2s | Qualification is on the property’s cash flow |
Third-party examples from six national DSCR lenders’ published program pages and guides, read October 6, 2026. Dated documents are from July to September 2026. These are not ALCOVA terms.
A higher score usually improves the terms. See how lenders read scores in our guide to the credit score needed to buy a house.
How much is the down payment on a DSCR loan?
Plan on 20 to 25 percent. ALCOVA’s page lists the down payment as typically 20 to 25 percent or more. Most published programs cap a purchase at 80 percent of value.
In Northern Virginia the ratio, not the lender’s cap, often sets the down payment. The next section shows why.
For down payment rules on a home you will live in, see our down payment guide.
Do DSCR loans work in Northern Virginia?
They can, but not at typical prices with 25 percent down. High values and today’s rates push the payment well above typical rents.
| County | Typical home value | PITIA with 25% down | Typical rent | DSCR | Rent needed for 1.00 |
|---|---|---|---|---|---|
| Loudoun | $795,391 | $4,840 | $2,940 | 0.61 | $4,840 |
| Fairfax | $760,599 | $4,859 | $2,537 | 0.52 | $4,859 |
| Arlington | $806,890 | $5,074 | $2,702 | 0.53 | $5,074 |
| Prince William | $581,036 | $3,660 | $2,280 | 0.62 | $3,660 |
Values: Zillow Home Value Index, August 2026. Rents: Zillow Observed Rent Index, August 2026, which includes apartments and likely understates rent on a house. Rate: 7.28%, the Freddie Mac 30-year average for conventional loans on October 1, 2026, used for illustration; ALCOVA says DSCR rates may be higher. Taxes at each county’s 2026 rate, including countywide levies, applied to the Zillow value; your assessment may differ. Insurance of $125 and dues of $100 a month are assumptions.
Single-family rents run higher. Zillow’s single-family rent index for the Washington metro area was $3,292 in August 2026. That figure is metro-wide, not county data. A home renting at that level would reach about 0.90 at the Prince William payment and about 0.68 at the Loudoun payment.
County tax rates are compared in our guide to Northern Virginia property tax rates.
What makes a deal reach 1.00?
| Lever | Effect in the Loudoun example |
|---|---|
| Larger down payment | About 60% down brings the ratio to 1.00 at $2,940 rent |
| Higher-rent property | At $3,292 rent, about 53% down reaches 1.00 |
| Lower price | A below-typical price lowers both the loan and the tax bill |
| Lender that accepts a ratio under 1.00 | Some do, often with tighter terms such as a higher score or a lower loan-to-value |
| Interest-only payment | Some programs offer it; the payment falls but the balance does not |
Calculated with the same assumptions as the table above.
DSCR loan vs conventional investment loan: what is the difference?
A conventional loan may carry a lower rate, but it verifies your income and caps how many properties you finance. A DSCR loan skips personal income and often allows an LLC.
| DSCR loan | Conventional (Fannie Mae) | |
|---|---|---|
| Qualifies on | Property rent | Your income and debts. 75% of the rent is set against the payment |
| Maximum loan-to-value, purchase | Commonly 80% | 85% for one unit; 75% for two to four units |
| Number of financed properties | Set by the lender | Up to 10 |
| Borrower | Often an LLC or an individual | A natural person, with limited exceptions such as certain trusts. An LLC is not among them |
| Prepayment penalty | Common | Not allowed on loans sold to Fannie Mae |
| Extra pricing for investment property | Not published as a separate charge; rates may be higher | 2.125% of the loan at 70.01% to 75% loan-to-value, before other adjustments |
Source: Fannie Mae Eligibility Matrix (August 5, 2026), Selling Guide A3-2-02, B2-2-01, B2-2-03, B3-3.1-08 and B3-3.8-02, and Loan-Level Price Adjustment Matrix (September 30, 2026); DSCR column from the lender examples above.
Fannie Mae also limits rent for new landlords. With less than 12 months of property management experience, rent can only offset the property’s payment. It cannot add to your income.
Standard investment loan rules are on our conventional loans page.
DSCR loans sit in a wider group of loans outside the standard rules. Our guide to non-QM loans explains how they differ from qualified mortgages.
Why does a DSCR loan not need income verification?
Because federal rules treat a loan on a rental you do not occupy as business credit. Regulation Z, which holds the ability-to-repay rule, does not cover credit that is primarily for a business purpose.
The official commentary says a loan to buy rental property that is not owner-occupied is deemed to be for business purposes. That stops applying if the owner expects to live there more than 14 days in the coming year.
Source: 12 CFR 1026.3(a) and official comment 3(a)-4, Consumer Financial Protection Bureau.
This is why you cannot use a DSCR loan for a home you will live in, and why lenders ask you to certify the property’s use.
Can you use a DSCR loan for an Airbnb in Northern Virginia?
In Fairfax and Arlington, generally not as the operator. Both counties allow short-term rentals only in the operator’s primary residence. An investor who does not live there cannot be the operator.
| County | Short-term rental rule |
|---|---|
| Fairfax | Operator must live in the home at least 185 days a year. Limit of 60 nights a year. Permit required |
| Arlington | Operator must live in the home at least 185 days a year. Annual permit required |
| Loudoun | Zoning permit and annual registration required. Whole-house rentals may need a special exception |
Source: Fairfax County, Short-Term Lodging; Arlington County, Accessory Homestay Permit; Loudoun County, Short-Term Rentals. Read October 6, 2026.
Other localities set their own rules. Check the zoning office before you underwrite a property on nightly rates.
Can you close a DSCR loan in an LLC?
Many DSCR lenders allow it. At least four of the published programs we read list LLC vesting.
Lenders may require the owners to guarantee the loan personally. Ask your attorney how an LLC fits your situation; this is not legal advice.
Do DSCR loans have prepayment penalties?
Often, yes. One national lender says the majority of DSCR loans carry one, and three published programs we read include one.
The federal limits in Regulation Z apply to consumer mortgages, not to business-purpose loans. State law can still restrict them.
| Structure | How it works |
|---|---|
| 5/4/3/2/1 step-down | 5% if you pay off in year one, falling 1 point a year |
| 3/2/1 step-down | 3% in year one, 2% in year two, 1% in year three |
| Six months of interest | Charged on the amount prepaid above a set share of the balance |
Source: published DSCR lender program guides (July and October 2026); 12 CFR 1026.43(g).
On a $596,543 loan, a 5 percent penalty is $29,827. If you plan to sell or refinance within a few years, price the penalty in.
Planning a later refinance? Compare the ways to take equity out in our guide to cash-out refinance vs HELOC.
What closing costs and taxes apply in Virginia?
Virginia charges a recordation tax on the deed and on the deed of trust. Each is 25 cents per $100, and a county or city may add one-third more.
On a $795,391 purchase with a $596,543 loan, the two taxes total about $4,640 including the local share.
Source: Va. Code 58.1-801, 58.1-803 and 58.1-814.
The other line items are covered in our guide to closing costs in Virginia.
As a landlord you also follow state rules. Virginia caps a security deposit at two months’ rent.
Source: Va. Code 55.1-1226.
What are the pros and cons of a DSCR loan?
The main benefit is qualifying without personal income documents. The main costs can be a larger down payment, a higher rate and, at many lenders, a prepayment penalty.
| Pros | Cons |
|---|---|
| No tax returns or W-2s in many cases | Larger down payment than a home you live in |
| Useful when write-offs lower your taxable income | Rates may be higher than conventional loans |
| LLC vesting at many lenders | Prepayment penalties are common |
| No 10-property cap at some lenders | Hard to reach a 1.00 ratio at Northern Virginia prices |
| Purchase or refinance | Cannot be used for a home you occupy |
Based on ALCOVA’s DSCR page and the published lender examples above.
On the tax side, the IRS lets owners depreciate a residential rental building over 27.5 years. Land is not depreciable. Ask a tax professional about your own return.
Source: IRS Publication 527 (2025).
Larger loans raise their own questions; see our guide to jumbo vs conforming loans.
For state programs and local market pages, visit our Virginia home loans page.

Get a Mortgage Estimate for Free
Send us the address and the rent, and see whether the numbers support a DSCR loan.
✓Free, no obligation✓Licensed in VA, MD, DC and WV✓Loan officer Ken Byrne, NMLS #187129
Frequently asked questions
What DSCR do lenders want?
It varies. One published program requires a ratio above 1.00. A 2025 ALCOVA article says lenders generally look for at least 1.25. Others accept less than 1.00 with tighter terms.
What credit score do you need for a DSCR loan?
Published minimums run from 620 to 680, depending on the lender. Higher scores open higher loan-to-value limits.
Can a first-time investor get a DSCR loan?
Some lenders allow it with tighter terms. One published program asks first-time investors for 12 months of reserves.
Can I live in a property financed with a DSCR loan?
No. These loans are for investment properties only. Occupying the home would take the loan outside the business-purpose rule it relies on.
Are DSCR loan rates higher than conventional rates?
They can be. ALCOVA says DSCR rates may be higher than traditional loan options. We found no official DSCR rate average, so compare written quotes.
How is rent verified for a DSCR loan?
Usually by the appraiser’s market rent estimate on a rent schedule such as Form 1007. A lender may also ask for the lease if the home is rented.
How many DSCR loans can I have?
It depends on the lender. Fannie Mae limits conventional borrowers to 10 financed properties; DSCR lenders set their own limits.
Do DSCR loans require reserves?
Often. Published examples range from 3 to 12 months of payments. ALCOVA says reserve requirements may apply.
Can I refinance out of a DSCR loan later?
Yes, but check the prepayment penalty first. Many run three to five years.
This article is general information, not financial or legal advice and not a commitment to lend or an offer of credit. Loan limits, program rules, premium schedules and rates change, and individual eligibility depends on a full review of your credit, income, assets and the property. Every figure here is an illustration, not a quote, built from published sources and a weekly survey average rather than underwriting decisions. Insurance and mortgage insurance amounts are planning estimates. Confirm anything you plan to act on with a licensed mortgage professional. Third-party lender terms are published examples read on October 6, 2026 and are not offers. Zillow and Freddie Mac figures were checked on October 6, 2026. Examples are illustrations, not quotes. This is not tax or legal advice.
Categories
Recent Posts










GET MORE INFORMATION

Broker Associate