
How to Read a Loan Estimate: What Can Change Before Closing
Some numbers on a Loan Estimate cannot legally move. Some can move by ten percent. Some can move by anything at all. The form does not tell you which is which.
Short answer: a Loan Estimate is a three page form your lender must send within three business days of receiving your application, and it is the only document that lets you compare lenders on equal terms. The part almost nobody is told is that the numbers on it carry three different levels of protection. Some cannot increase by a cent. Some can increase by up to ten percent as a group. Some can increase without limit. Reading it well means knowing which bucket each line sits in, because that is what decides whether a higher number at closing is a surprise or a violation.
By Ken Byrne, NMLS #187129 · ALCOVA Mortgage LLC, NMLS #40508 · Updated September 2026
Most guides to the Loan Estimate walk you through the boxes and stop. That tells you what the form says and nothing about what it is worth. This one goes through the same form from the other direction: what is legally binding, what is merely estimated, what is a guess, when a lender is allowed to send you a new one, and what a lender may not do before you have it. Every rule here is quoted from Regulation Z rather than paraphrased. If you want a second pair of eyes on an estimate you are holding right now, send it over and JB Financing mortgage will read it line by line with you.
What a Loan Estimate is, and the six items that start the clock
A Loan Estimate is the standardized disclosure a lender must give you after you apply for most mortgages. It replaced the old Good Faith Estimate and Truth in Lending statement in 2015. Every lender uses the same form in the same order, which is the entire point: it makes offers comparable.
The timing rule is where people get confused, because the clock does not start when you feel like you have applied. Regulation Z defines an application as six specific pieces of information, and once a lender holds all six, it has an application whether or not it has everything it needs to underwrite you.
| The six items that constitute an application | Why it matters |
|---|---|
| Your name | Withholding any one of these six delays the clock |
| Your income | A lender cannot start the three day period without them |
| Your Social Security number, to pull credit | This is usually the last one people give |
| The property address | On a pre-approval with no property yet, there is no application |
| An estimate of the property value | So no Loan Estimate is owed at that stage |
| The loan amount you are seeking | Supplying all six is what triggers the disclosure |
12 CFR 1026.2(a)(3). Once the creditor receives all six items it has received an application for the purposes of 1026.19, "even if the creditor requires additional information".
This is why a pre-approval letter rarely comes with a Loan Estimate. Without a property address and a value estimate there is no application in the regulatory sense, so no disclosure is owed. That is not a lender being evasive. It is the rule working as written. Once you are under contract and the address goes in, the three day clock starts.
| Deadline | What has to happen |
|---|---|
| Three business days after application | The lender delivers or mails the Loan Estimate |
| Seven business days before consummation | You must have received it |
| Three business days before consummation | You must have received the Closing Disclosure |
| Four business days before consummation | The last point a revised Loan Estimate can be provided |
12 CFR 1026.19(e)(1)(iii), 1026.19(f)(1)(ii) and 1026.19(e)(4). Business days here follow the regulation’s own definition, which is not the same as working days in ordinary speech.
What appears on a Loan Estimate, page by page
Three pages, always in the same order. If you are comparing two lenders, compare the same page of each rather than reading one front to back and then the other.
Page 1: the loan itself
Loan Terms at the top: amount, interest rate, monthly principal and interest, and three yes or no questions about whether any of those can increase after closing. Then Projected Payments, which builds the full monthly figure including estimated escrow. Then Costs at Closing, the two summary numbers everyone jumps to.
Page 2: where the money actually goes
This is the page that matters. Loan Costs are split into section A origination charges, section B services you cannot shop for, and section C services you can shop for. Other Costs are section E taxes and government fees, section F prepaids, section G the initial escrow deposit, and section H other. The lettering is not decoration. It is how the tolerance rules are applied, which is the next section of this guide.
Page 3: the comparisons
In five years, showing total paid and principal paid. The annual percentage rate. The total interest percentage. Then Other Considerations and a confirm receipt line. Signing the receipt confirms you got the form. It does not commit you to the loan and it is not an intent to proceed.
Estimated escrow is not a fee. Section G is money being collected and held for your own property tax and insurance bills, and the monthly escrow figure inside Projected Payments is the same money spread out. It is the line most often mistaken for a lender charge when comparing two offers. If one lender shows a much larger escrow figure, that usually reflects a different assumption about your tax bill rather than a worse deal. Our guide to how an escrow account works covers the mechanics.

“Send me the Loan Estimate you already have and I will tell you which numbers on it are locked, which can move, and whether anything is sitting in the wrong section.”
Arslan Jamil, Broker Associate
Loans originated by Ken Byrne, NMLS ID# 187129 · ALCOVA Mortgage LLC, NMLS ID# 40508. Equal Housing Lender.
The three buckets: which numbers are promises and which are guesses
Here is the part that turns the form from a list into a tool. Regulation Z sorts every charge into one of three tolerance categories, and the category decides what happens if the number at closing is higher than the number you were shown.
| Bucket | What it covers | How much it may increase |
|---|---|---|
| Zero tolerance | Lender charges, and anything you were not allowed to shop for | Not at all. The charge paid cannot exceed the amount disclosed |
| Ten percent aggregate | Third party services you chose from the lender’s written list, and recording fees | Up to ten percent, measured across the whole group rather than line by line |
| Unlimited | Prepaid interest, property insurance premiums, escrow deposits, providers you found yourself, and third party services the lender did not require | By any amount |
12 CFR 1026.19(e)(3). The general rule is that an estimate is in good faith "if the charge paid by or imposed on the consumer does not exceed the amount originally disclosed". The ten percent rule applies to "the aggregate amount of charges for third-party services and recording fees". The unlimited list names prepaid interest, property insurance premiums, amounts placed into escrow, "charges paid to third-party service providers selected by the consumer", and third party services the creditor did not require.
The ten percent is a group test, not a per line test. One charge in that bucket can double and there is still no breach, provided the whole bucket has not risen by more than ten percent against the original total. That is why comparing a single line between the Loan Estimate and the Closing Disclosure tells you very little, and comparing the section totals tells you a great deal.
If a zero tolerance charge does increase, or the ten percent group goes over, the lender has to refund the excess. In practice that cure appears as a lender credit on the Closing Disclosure. Knowing which bucket a line sits in is the difference between noticing that and signing past it.
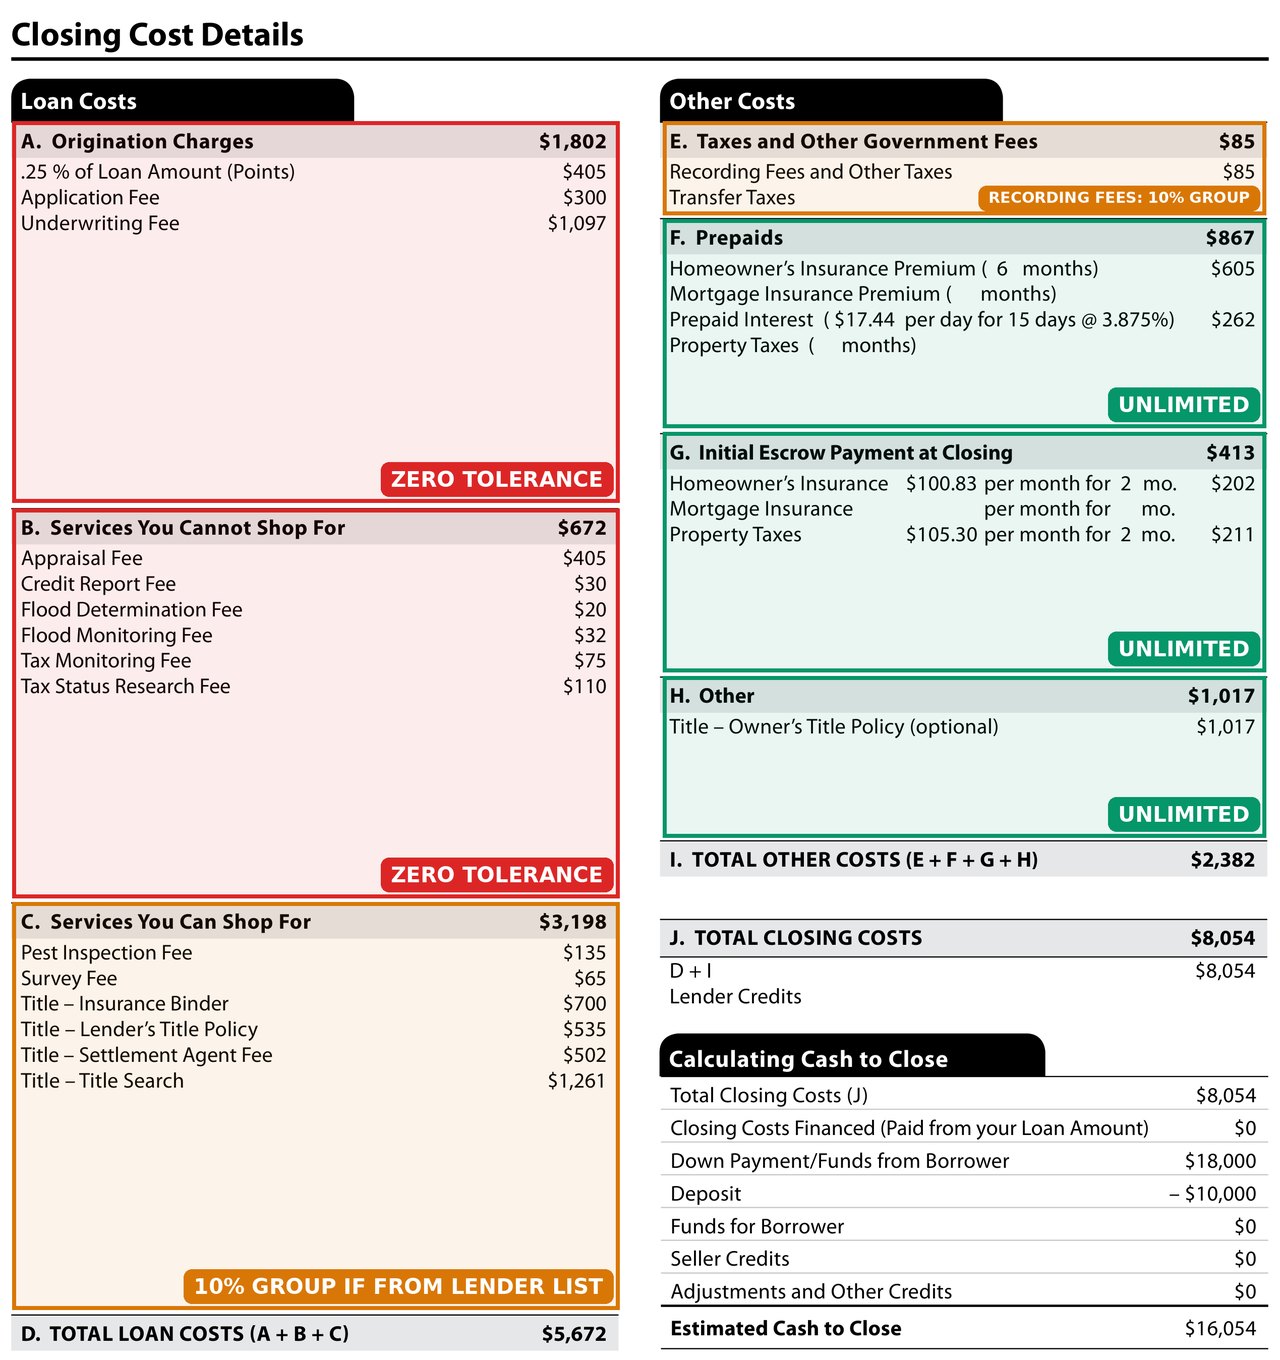
Page two of the CFPB’s sample Loan Estimate for a fictional borrower, with the Regulation Z tolerance buckets marked. Section C is in the ten percent group only for providers picked from the lender’s written list; a provider you find yourself moves that line to unlimited. Source: Consumer Financial Protection Bureau.
When a revised Loan Estimate is required, and when it is just allowed
A lender cannot simply reissue a better looking Loan Estimate because the first one did not work out. A revised estimate only resets the tolerance baseline for one of six listed reasons.
| Reason a revised Loan Estimate may reset tolerances | In plain terms |
|---|---|
| A changed circumstance causes an estimated charge to increase | Something outside the lender’s control changed, such as an unexpected condition at the property |
| A changed circumstance affects your eligibility | Your creditworthiness or the value of the security changed after the first estimate |
| You request a change to the credit terms or the settlement | You asked for a different product, term or closing date |
| The rate was not locked and points or lender credits changed | Interest rate dependent charges move with the market until you lock |
| You indicate intent to proceed more than ten business days after the estimate | The original figures have simply gone stale |
| A construction loan where settlement will occur more than sixty days out | A specific allowance for long build timelines |
12 CFR 1026.19(e)(3)(iv). Under 1026.19(e)(4) the revised disclosure must be provided "within three business days of receiving information sufficient to establish that one of the reasons for revision applies", and not later than four business days before consummation.
What is not on that list matters more than what is. A lender discovering it underquoted, a processor noticing an error, or a fee the lender simply forgot are not changed circumstances. If a charge in the zero tolerance bucket rises for one of those reasons, the lender owes you the difference. Ask which of the six reasons applies and ask for it in writing.
What a lender may not do before you have the Loan Estimate
There is a hard prohibition here and it is worth knowing, because it is the most common place a rushed process crosses a line.
A lender may not charge you a fee in connection with your application before you have received the Loan Estimate and have told the lender you intend to proceed. The single exception is a bona fide and reasonable fee for a credit report. No application fee, no appraisal fee, no processing or underwriting deposit, and no lock fee before both of those things have happened.
12 CFR 1026.19(e)(2)(i). The regulation states that "a creditor or other person may not impose a fee on a consumer in connection with the consumer’s application" before the consumer has received the Loan Estimate and "has indicated intent to proceed with the transaction".
Intent to proceed has to come from you. Silence is not intent. Neither is signing the confirm receipt line on page three, which only acknowledges that the form reached you. A lender that takes a card number for an appraisal the same afternoon you first spoke, before any estimate arrived, has got the order wrong.
How to compare two Loan Estimates without fooling yourself
The comparison that matters is narrower than the form suggests, because large parts of it are not the lender talking about itself.
| Compare closely | Treat with caution | Why |
|---|---|---|
| Section A origination charges | Section F prepaids | Section A is the lender. Prepaids depend on your closing date |
| Section B services you cannot shop for | Section G initial escrow deposit | Escrow is your own tax and insurance money, not a charge |
| The interest rate and any points | Section E government fees | Government fees are the same for everyone in the same county |
| Lender credits | Estimated property tax | Two lenders can assume different tax figures for the same house |
| The annual percentage rate on page three | The five year comparison | APR folds cost into rate; the five year figure assumes you stay |
One practical rule. Get the estimates on the same day if you possibly can, because rate dependent charges move daily and a two day gap can make a worse offer look better. The wider process around all this is set out in our step by step guide to pre-approval in Northern Virginia.
In Virginia, section E will look alarming, and it should. Virginia charges recordation tax on the deed and again on the deed of trust, roughly $3.33 per $1,000 on the price and the same again on the loan. That is why government fees on a Virginia estimate run well above what a national calculator predicts. Recording fees sit in the ten percent bucket, so this is one of the few places a tolerance breach actually becomes visible. The full sheet is in our guide to what Virginia buyers pay at closing.
Comparing two or three lenders right now?
Arslan Jamil, Broker Associate
Send me all of the estimates rather than just the one you like. Most of the difference between offers at this stage is sitting in sections A, B and C, and the summary box on page one is the worst place to look for it. I will line them up properly and tell you what is actually different.
Loans originated by Ken Byrne, NMLS ID# 187129 · ALCOVA Mortgage LLC, NMLS ID# 40508. Equal Housing Lender.
What restarts the three day wait before closing, and what does not
Once the Closing Disclosure is issued you must have it three business days before consummation. Buyers are often told that any late change will push the closing. Three things do. Nothing else does.
Our guide to what a Closing Disclosure is explains the three-day rule, what restarts it and what to check on each page.
| Change | Does it restart the three day clock? |
|---|---|
| The annual percentage rate becomes inaccurate | Yes |
| The loan product changes, for example fixed to adjustable | Yes |
| A prepayment penalty is added | Yes |
| A fee goes up | No |
| A seller credit changes | No |
| The escrow figure is corrected | No |
| The cash to close moves | No |
12 CFR 1026.19(f)(2)(ii). Only those three listed changes require a corrected Closing Disclosure and a new three business day waiting period.
This is worth knowing in both directions. It stops a lender using a minor correction as cover for a delay, and it stops you panicking when a number moves on the Wednesday before a Friday closing. For how the whole timeline fits together, see our guide to how long it takes to close on a house.
And if you are earlier in the process than this, the Loan Estimate is one document in a longer sequence. What happens on either side of it is covered in our walkthrough of what happens after you are pre-approved.
The size of the payment those numbers add up to is a separate question, and one your debt-to-income ratio decides rather than the form. Every program ceiling is set out in our guide to the maximum DTI by loan type.
One last note on scope. Everything above applies to the standard closed-end mortgage most buyers use, which in practice means a conventional loan or a government-backed one. Home equity lines, reverse mortgages and a few other products sit under different disclosure rules and do not use this form at all.
Frequently asked questions
What is a loan estimate?
A three page standardized form a lender must provide within three business days of receiving your mortgage application. It sets out the loan terms, the projected monthly payment, and an itemized breakdown of closing costs, in a fixed layout every lender must use so that offers can be compared directly.
What appears on a loan estimate?
Page one carries loan terms, projected payments and costs at closing. Page two itemizes the costs in lettered sections: A origination charges, B services you cannot shop for, C services you can shop for, E taxes and government fees, F prepaids, G initial escrow deposit and H other. Page three has the five year comparison, the annual percentage rate, the total interest percentage and other considerations.
A revised loan estimate is required when?
A revised Loan Estimate may reset tolerances only for six listed reasons: a changed circumstance increasing a charge, a changed circumstance affecting your eligibility, revisions you request, points or credits changing because the rate was not locked, your intent to proceed arriving more than ten business days after the estimate, and a construction loan settling more than sixty days out. It must be provided within three business days of the lender learning of the reason, and no later than four business days before consummation.
Locking your rate is what keeps points and lender credits from moving on a revised estimate. Our guide to mortgage rate locks explains lock periods, extensions and float-downs.
What actions are prohibited before providing a loan estimate?
A lender may not impose any fee in connection with your application before you have received the Loan Estimate and have indicated your intent to proceed. The only exception is a bona fide and reasonable credit report fee. That rules out application, appraisal, processing and lock fees taken up front.
What is estimated escrow on a loan estimate?
It is the monthly amount the lender will collect from you and hold to pay your property tax and homeowners insurance when those bills fall due. It appears inside Projected Payments on page one, and the up front deposit into the account appears as section G on page two. It is your money being held on your behalf, not a lender charge, which is why it should not be treated as a cost when comparing two lenders.
Is a loan estimate the same as a pre-approval?
No. A pre-approval is the lender’s view of what you can borrow. A Loan Estimate is a regulated disclosure about a specific loan on a specific property, and it is only owed once the lender holds all six items that constitute an application, which includes the property address and a value estimate.
Can closing costs be higher than the loan estimate?
Some can and some cannot. Lender charges and services you could not shop for cannot increase at all. Third party services you chose from the lender’s list, together with recording fees, can increase by up to ten percent as a group. Prepaid interest, insurance premiums, escrow deposits and any provider you found yourself can increase without limit.
Does signing a loan estimate commit me to the loan?
No. The signature line on page three confirms only that you received the form. It is not an application, not an acceptance, and not the intent to proceed that a lender needs before charging you a fee. Intent to proceed has to be communicated separately and deliberately.
How long is a loan estimate good for?
The estimated closing costs are generally available to you for ten business days. If you indicate intent to proceed after that window, the lender may issue a revised Loan Estimate and reset the tolerance baseline on that basis alone, without anything else having changed.
What happens if my lender breaches a tolerance?
The lender must refund the excess. It normally appears as a lender credit on the Closing Disclosure rather than as a separate payment. This is one reason to compare section totals between the Loan Estimate and the Closing Disclosure before you sign rather than afterwards.
“Send me your Loan Estimate, or all of them if you are comparing. I will tell you which numbers are locked, which can move, what is missing, and what the real difference between the offers is.”
Arslan Jamil, Broker Associate
Loans originated by Ken Byrne, NMLS ID# 187129 · ALCOVA Mortgage LLC, NMLS ID# 40508. Equal Housing Lender.
This article is general information, not financial or legal advice and not a commitment to lend or an offer of credit. Loan limits, program rules, premium schedules and rates change, and individual eligibility depends on a full review of your credit, income, assets and the property. Every figure here is an illustration, not a quote, built from published sources and a weekly survey average rather than underwriting decisions. Insurance and mortgage insurance amounts are planning estimates. Confirm anything you plan to act on with a licensed mortgage professional. Regulation Z citations here are to 12 CFR part 1026 as published and are summarized for a general audience rather than reproduced in full. Rules are amended periodically and individual transactions vary. This is general information, not legal advice. Confirm anything you plan to act on with your lender, your settlement agent or an attorney.
Categories
Recent Posts










GET MORE INFORMATION

Broker Associate