
VA Loan Funding Fee 2026: Rate Chart, Exemptions and How to Lower It
The VA funding fee is a one-time charge. Many veterans never pay it, and those who do can sometimes lower it.
Short answer: on a 2026 VA purchase loan with less than 5 percent down, the funding fee is 2.15 percent of the loan the first time you use the benefit and 3.3 percent after that. Put 5 percent down and it drops to 1.5 percent; 10 percent down brings it to 1.25 percent. On a $650,000 home with no down payment that is $13,975 for a first-time user. Veterans who receive VA disability compensation, Purple Heart recipients on active duty and eligible surviving spouses pay nothing.
By Ken Byrne, NMLS #187129 · ALCOVA Mortgage LLC, NMLS #40508 · Updated October 2026
For veterans who are not exempt, the funding fee can be one of the largest closing costs on a VA loan, and the rules around it are easy to misread. This guide covers the 2026 rates for every VA loan type, what the fee costs at Virginia, Maryland and DC home prices, who is exempt, how a pending disability claim can lead to a refund, and the legal ways to lower the fee. For numbers on your own purchase, talk to JB Financing, the Ken Byrne Team at ALCOVA Mortgage.
What is the VA funding fee?
The Department of Veterans Affairs describes it as a one-time payment that the veteran, service member or survivor pays on a VA-backed or VA direct home loan. Federal law sets the fee as a percentage of the loan amount, and the money goes to VA to help cover the cost of the loan guaranty program. It is charged once, at closing. There is no monthly version of it.
That is the key difference from other low down payment loans. VA states that its purchase loans need no private mortgage insurance and no mortgage insurance premiums, so the funding fee takes the place of years of monthly charges. How those monthly charges work on other loans is in our guide to PMI costs.
VA.gov, VA funding fee and loan closing costs (last updated September 22, 2026); 38 U.S.C. 3729; VA.gov, Purchase loan (last updated January 7, 2026).
VA funding fee chart for 2026
The rate depends on three things: the type of loan, your down payment and whether you have had a VA loan before. These rates apply to loans closed on or after April 7, 2023.
| Down payment on a purchase or construction loan | First use | After first use |
|---|---|---|
| Less than 5% | 2.15% | 3.3% |
| 5% or more, but less than 10% | 1.5% | 1.5% |
| 10% or more | 1.25% | 1.25% |
VA.gov funding fee rate charts; 38 U.S.C. 3729(b). The fee is a percentage of the loan amount, not the purchase price.
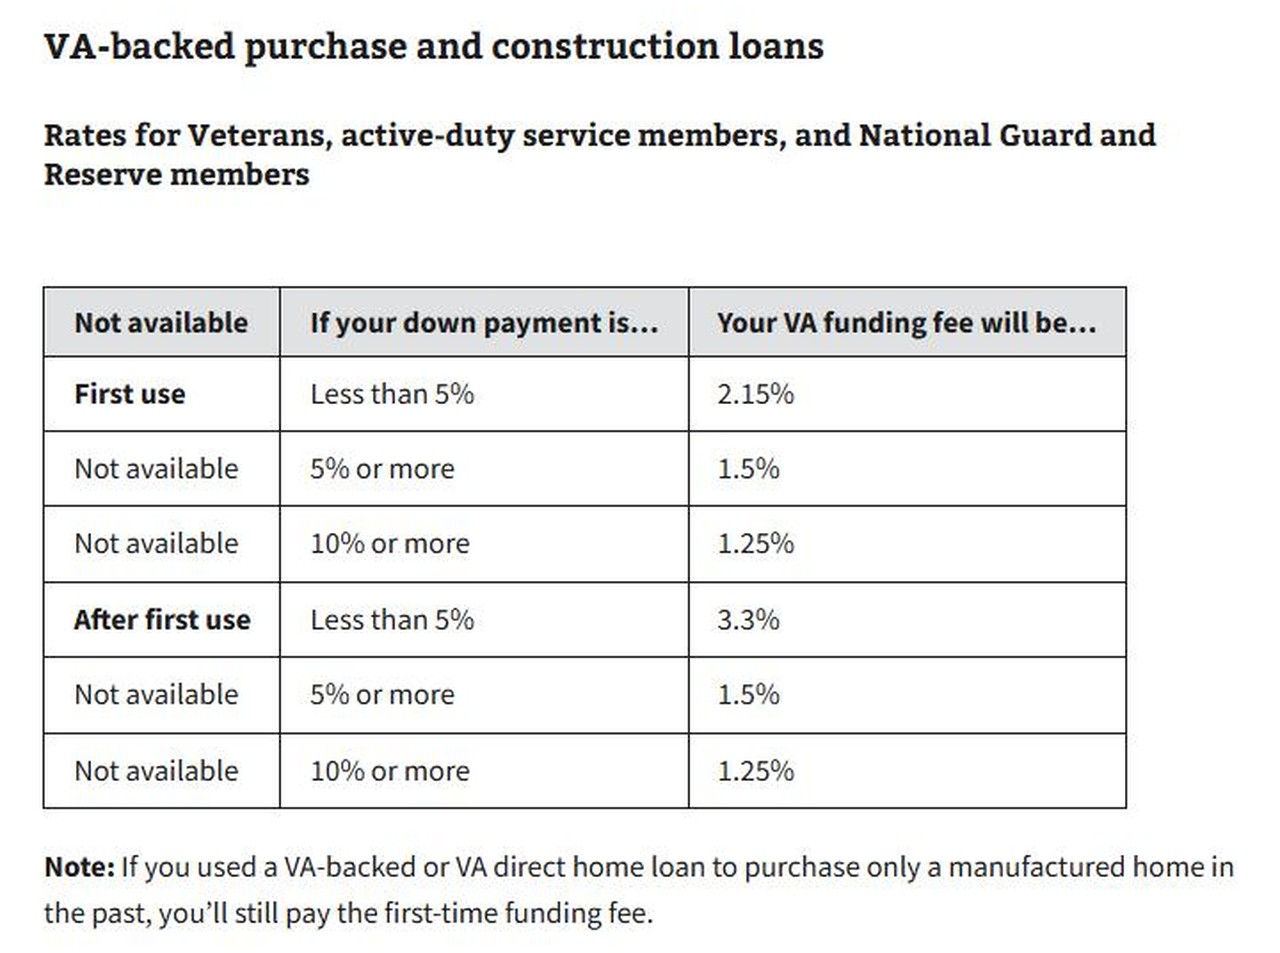
The official rate chart for purchase and construction loans, as displayed on October 5, 2026. Blank cells in the first column show as “Not available” on the page; those rows belong to the group above them. Source: U.S. Department of Veterans Affairs, VA.gov.
Rates for other VA loan types
| Loan type | Funding fee |
|---|---|
| Cash-out refinance, first use | 2.15% |
| Cash-out refinance, after first use | 3.3% |
| Interest Rate Reduction Refinance Loan (IRRRL) | 0.5% |
| Loan assumption | 0.5% |
| Manufactured home loan, not permanently affixed | 1% |
| Native American Direct Loan, purchase | 1.25% |
| Native American Direct Loan, refinance | 0.5% |
| Vendee loan to buy a VA-acquired property | 2.25% |
VA.gov funding fee rate charts (last updated September 22, 2026).
To see how the funding fee stacks up against PMI, read our VA vs conventional loan cost comparison.
National Guard and Reserve members pay the same rates as active-duty veterans. Before January 1, 2020 they paid a quarter point more on most purchase loans, and some older web pages still say so. Service requirements for each group are in our guide to VA loan eligibility.
Will the rates change?
No change has been enacted for 2026. Under current law these rates apply to loans closed before June 9, 2034. For loans closed on or after that date, the statute schedules lower rates: 1.40 percent for a first loan with no down payment and 1.25 percent for later loans. Congress has moved that end date several times, most recently in January 2025, so treat the 2034 date as current law, not a promise. A bill that passed the House in May 2026 (H.R. 6047) would extend the end date and raise the fee on IRRRLs and assumptions. It was referred to a Senate committee in June and had not become law when we checked on October 5, 2026.
38 U.S.C. 3729(b)(2), as amended by Public Law 118-210; H.R. 6047, 119th Congress, as received in the Senate June 2, 2026.
How to calculate the VA funding fee at DMV home prices
| Home price | Down payment | Loan amount | First use | After first use |
|---|---|---|---|---|
| $500,000 | None | $500,000 | $10,750 | $16,500 |
| $500,000 | 5% ($25,000) | $475,000 | $7,125 | $7,125 |
| $500,000 | 10% ($50,000) | $450,000 | $5,625 | $5,625 |
| $650,000 | None | $650,000 | $13,975 | $21,450 |
| $650,000 | 5% ($32,500) | $617,500 | $9,262.50 | $9,262.50 |
| $650,000 | 10% ($65,000) | $585,000 | $7,312.50 | $7,312.50 |
| $800,000 | None | $800,000 | $17,200 | $26,400 |
| $800,000 | 5% ($40,000) | $760,000 | $11,400 | $11,400 |
| $800,000 | 10% ($80,000) | $720,000 | $9,000 | $9,000 |
Calculated from the VA.gov rates: loan amount times the rate.
The jump at 5 percent down matters most for repeat users. On an $800,000 home, a veteran using the benefit a second time pays $26,400 with no down payment and $11,400 with 5 percent down, a $15,000 difference. Being a few hundred dollars short of 5 percent costs the full higher rate, so check the exact figure with your loan officer. How much you can borrow with no down payment is covered in our guide to VA loan limits in the DMV.

Get a Mortgage Estimate for Free
See your VA loan payment with the funding fee paid at closing or financed.
✓Free, no obligation✓Licensed in VA, MD, DC and WV✓Loan officer Ken Byrne, NMLS #187129
VA funding fee exemption: who does not pay
VA lists five groups who do not pay the fee:
| You do not pay if | Detail |
|---|---|
| You receive VA compensation for a service-connected disability | Any rating that pays VA compensation. A 0 percent rating that pays nothing does not qualify by itself |
| You are eligible for that compensation but receive retirement or active-duty pay instead | The entitlement counts, even if you are not drawing the benefit |
| You are a surviving spouse receiving Dependency and Indemnity Compensation (DIC) | Surviving spouse of a veteran who died in service or from a service-connected disability |
| You are a service member with a proposed or memorandum rating from a pre-discharge claim | The rating must be dated before the loan closing date |
| You are on active duty and have been awarded the Purple Heart | You must give evidence on or before the closing date |
VA.gov, VA funding fee and loan closing costs; 38 U.S.C. 3729(c); VA Circular 26-19-30.
This is a large group. VA reported in June 2026 that since 2021 more than half of the veterans who obtained a VA-guaranteed home loan were exempt from the fee. Ask your lender to confirm your status early, because it changes your closing costs by thousands of dollars. More on using the benefit in this area is in our military homebuyers guide.
First use vs after first use
The higher 3.3 percent rate applies when you have had a VA-backed or VA direct home loan before and you put less than 5 percent down. Three details catch people out:
| Situation | Rate that applies |
|---|---|
| You paid off your first VA loan and sold the home | After first use. Restoring your entitlement does not reset the fee |
| Your only earlier VA loan was for a manufactured home | First use |
| Your earlier VA-financed home was substantially damaged or destroyed in a presidentially declared major disaster, and your next VA loan, made within three years, is only to repair or rebuild it | First use |
| You put 5% or more down | The same 1.5% or 1.25% whether or not you have used the benefit |
38 U.S.C. 3729(b)(4); VA.gov rate chart notes.
How to avoid or lower the VA funding fee
Confirm an exemption before you close
If you have a service-connected condition and have never filed a claim, the timing matters. If you are receiving VA disability compensation before closing, or you have a pre-discharge proposed or memorandum rating that says you are eligible for it, the fee is waived. A proposed or memorandum rating that arrives after closing does not waive it, according to VA.
Put 5 or 10 percent down
On a $650,000 home, 5 percent down ($32,500) cuts a first-time fee from $13,975 to $9,262.50, and a repeat-use fee from $21,450 to $9,262.50. Whether that is the best use of your cash depends on your reserves and other goals. VA says no down payment is needed as long as the sales price is not higher than the home’s appraised value, though a lender may ask for one in some cases.
Ask the seller to pay it
VA allows the seller to credit the funding fee. It counts as a seller concession, and VA limits concessions to 4 percent of the home’s reasonable value, which is $26,000 if the home appraises at $650,000. Ordinary closing costs paid by the seller are treated separately. What those costs look like locally is in our guide to closing costs in Virginia.
Our guide to seller concessions compares VA's 4% limit with the conventional, FHA and USDA limits.
Assume an existing VA loan
The fee on a loan assumption is 0.5 percent of the unpaid balance. The buyer has to be approved as creditworthy by the loan holder or VA, and you must cover the gap between the price and the loan balance.
VA funding fee refund after a pending disability claim
A claim that is still pending on closing day does not waive the fee. You pay it, and VA says you may be eligible for a refund if you are later awarded compensation with an effective date before your loan closing date. VA’s loan guaranty site says refunds issued on or after July 1, 2019 are paid directly to the veteran, regardless of the loan balance. To request one, contact your loan servicer or call a VA regional loan center at 877-827-3702, Monday through Friday, 8 a.m. to 6 p.m. Eastern.
VA.gov; VA Loan Guaranty Service, funding fee page; VA News, June 11, 2026; 38 U.S.C. 3714 (assumptions).
Get Pre-Approved Today
Get pre-approved and find out which funding fee rate applies to your VA loan.
✓Free, no obligation✓Licensed in VA, MD, DC and WV✓Loan officer Ken Byrne, NMLS #187129
Pay the fee at closing or finance it?
You can pay the fee in cash at closing or add it to the loan. On a purchase, the funding fee is the only closing cost VA lets you finance. Financing keeps cash in your pocket but you pay interest on it.
| Home price, no down payment, first use | Fee | Added monthly payment if financed | Total loan |
|---|---|---|---|
| $500,000 | $10,750 | About $74 | $510,750 |
| $650,000 | $13,975 | About $96 | $663,975 |
| $800,000 | $17,200 | About $118 | $817,200 |
Principal and interest on the fee alone, 30-year fixed at 7.28% (Freddie Mac Primary Mortgage Market Survey average for conventional 30-year fixed loans, October 1, 2026). An illustration only; VA loan rates differ by lender and borrower.
Kept for all 30 years at that rate, a financed $13,975 fee costs about $34,400 in payments. Most loans are sold or refinanced well before then, but the point stands: if you have the cash and no better use for it, paying at closing is cheaper. Program details are on our VA loans page.
Funding fee on a VA refinance
An IRRRL, the VA streamline refinance, carries a 0.5 percent fee: $2,500 on a $500,000 loan. A VA cash-out refinance is charged like a purchase with no down payment, 2.15 percent for first use and 3.3 percent after, so $10,750 or $16,500 on $500,000. The exemptions above apply to refinances too. See current options on our refinance page.
Is the VA funding fee tax deductible in 2026?
For some households, yes. This is general tax information, not advice. The federal deduction for mortgage insurance premiums expired after 2021, and the tax law signed on July 4, 2025 restored it for tax years beginning after December 31, 2025. The law’s definition of qualified mortgage insurance includes insurance provided by the Department of Veterans Affairs, which the IRS described as the funding fee when the deduction last applied. It is treated as mortgage interest if you itemize and the loan was used to buy, build or substantially improve the home. The deduction shrinks by 10 percent for each $1,000 of adjusted gross income over $100,000, so it is gone above $109,000 ($54,500 if married filing separately). The IRS had not published its 2026 guidance when we checked, so confirm with a tax professional.
26 U.S.C. 163(h)(3)(E) and (F), as amended by Public Law 119-21, section 70108; 26 CFR 1.163-11.
Other VA closing cost rules worth knowing
| Rule | What it means |
|---|---|
| 1% origination cap | A lender may charge a flat fee of up to 1 percent of the loan in place of other origination charges |
| Only listed fees allowed | Beyond that, the borrower can pay only itemized costs such as the appraisal, credit report, title work, recording fees and prepaid taxes and insurance |
| 4% seller concession limit | Covers extras such as a funding fee credit, debt payoff or prepaid insurance |
| Financing | On a purchase, only the funding fee can be added to the loan |
38 CFR 36.4313; VA.gov, VA funding fee and loan closing costs.
VA loans by the numbers
| Fiscal year 2025 | Figure |
|---|---|
| VA loans guaranteed | 528,340 |
| Total loan volume | $206.1 billion |
| Average loan amount | $390,101 |
| Purchase loans | 323,832 |
| Purchase loans with no down payment | 240,749 |
| First-time homebuyers | 130,238 |
Veterans Benefits Administration, Annual Benefits Report, fiscal year 2025, Loan Guaranty. National figures.
Frequently asked questions
How much is the VA funding fee in 2026?
On a purchase with less than 5 percent down, 2.15 percent of the loan for first use and 3.3 percent after first use. With 5 percent down it is 1.5 percent, and with 10 percent or more it is 1.25 percent.
Who is exempt from the VA funding fee?
Veterans receiving VA disability compensation, those eligible for it but receiving retirement or active-duty pay instead, surviving spouses receiving DIC, service members with a pre-discharge proposed or memorandum rating dated before closing, and active-duty Purple Heart recipients.
Can the VA funding fee be rolled into the loan?
Yes. Federal law allows the fee to be included in the loan and paid from the proceeds. On a $650,000 loan the first-use fee of $13,975 adds about $96 a month at a 7.28 percent rate.
Is the funding fee higher the second time I use a VA loan?
Only if you put less than 5 percent down. Then it is 3.3 percent instead of 2.15 percent. With 5 percent or more down, first and later uses pay the same rate.
Can I get a VA funding fee refund?
Possibly, if you are later awarded VA disability compensation with an effective date before your loan closing date. Contact your servicer or a VA regional loan center at 877-827-3702.
Can the seller pay the VA funding fee?
Yes. It counts as a seller concession, and VA limits concessions to 4 percent of the home’s reasonable value.
Do National Guard and Reserve members pay a higher funding fee?
No. Since January 1, 2020 they pay the same rates as other veterans.
What is the funding fee on a VA streamline refinance?
An Interest Rate Reduction Refinance Loan has a 0.5 percent funding fee, regardless of prior use.
Does a VA loan have PMI?
No. VA loans have no private mortgage insurance and no monthly mortgage insurance premium. The one-time funding fee is the program’s charge.
Next stepStart Your Pre-Approval
Start online, and Ken Byrne’s team will walk through your VA loan costs line by line.
✓Free, no obligation✓Licensed in VA, MD, DC and WV✓Loan officer Ken Byrne, NMLS #187129
This article is general information, not financial or legal advice and not a commitment to lend or an offer of credit. Loan limits, program rules, premium schedules and rates change, and individual eligibility depends on a full review of your credit, income, assets and the property. Every figure here is an illustration, not a quote, built from published sources and a weekly survey average rather than underwriting decisions. Insurance and mortgage insurance amounts are planning estimates. Confirm anything you plan to act on with a licensed mortgage professional. VA rates and rules were checked against VA.gov and federal law on October 5, 2026. Fee amounts are calculations, not quotes. This is not tax advice.
Categories
Recent Posts










GET MORE INFORMATION

Broker Associate