
Buying a House With Student Loan Debt: How Each Loan Program Counts It
Student loans don't automatically stop a purchase; what matters is the monthly payment your lender counts.
Short answer: yes, you can buy a house with student loan debt. Lenders count a monthly student loan payment in your debt-to-income ratio, and the rules depend on the loan. If your credit report shows a $0 payment, FHA, USDA and Freddie Mac count 0.5% of the balance each month, Fannie Mae can accept a documented $0 income-driven payment, and VA uses 5% of the balance divided by 12 unless the loan is deferred at least 12 months past closing or a recent servicer statement documents a lower payment.
By Ken Byrne, NMLS #187129 · ALCOVA Mortgage LLC, NMLS #40508 · Updated October 2026
Student loans are a common reason buyers think they are not ready, but the balance itself is not what lenders look at. They look at the monthly payment they must count, and each loan program counts it differently. That difference can change your buying power by tens of thousands of dollars.
If you have student loans and want to know which loan counts them best, JB Financing mortgage specialists can run the numbers with you.
Can you buy a house with student loan debt?
Yes. Lenders add your housing payment to your other monthly debts, including student loans, and compare the total with your gross monthly income. That debt-to-income ratio has benchmarks: up to 50% for Fannie Mae loans approved through its automated system, 43% for manually underwritten FHA loans without compensating factors, 41% as VA's guideline, and 41% total for USDA, up to 44% with a waiver. Our guide to debt-to-income ratio and mortgage approval explains how the ratio works.
How do lenders calculate student loan payments?
| Loan program | Payment above $0 on credit report | $0 or no payment reported | Deferred or in forbearance |
|---|---|---|---|
| Conventional, Fannie Mae | Use the reported payment, or the statement if the report is wrong | Documented $0 income-driven payment can be used; otherwise 1% of the balance or a fully amortizing payment | 1% of the balance or a fully amortizing payment |
| Conventional, Freddie Mac | Use the reported payment | 0.5% of the outstanding balance, including income-driven plans | Counted under Freddie Mac's rules; confirm with your lender |
| FHA | Use the reported or documented payment | 0.5% of the outstanding balance | 0.5% of the balance when the credit report shows $0 |
| VA | The greater of the reported payment or 5% of the balance divided by 12 | 5% of the balance divided by 12 | Excluded if deferred at least 12 months past closing |
| USDA | Use the reported or documented payment | 0.5% of the outstanding balance | 0.5% of the balance when the credit report shows $0 |
Fannie Mae Selling Guide B3-6-05; Freddie Mac LPA update effective September 28, 2025; HUD Mortgagee Letter 2021-13; VA Circular 26-17-02 and VA lender training; USDA HB-1-3555 Chapter 11. Checked October 23, 2026.
How does Fannie Mae count student loans?
For conventional loans sold to Fannie Mae, the lender uses the monthly payment on your credit report, or the payment on your latest student loan statement if the report is wrong. If you are on an income-driven repayment plan and your payment is truly $0, the lender can document that and qualify you with a $0 payment.
For loans in deferment or forbearance, the lender counts 1% of the outstanding balance or a fully amortizing payment based on the loan terms. If someone else, such as a parent, has been making your payments, the debt can sometimes be excluded with 12 months of their canceled checks or bank statements showing on-time payments.
How does Freddie Mac count student loans?
Freddie Mac takes a stricter approach to $0 payments. Under Freddie Mac's current rules (most recently updated September 28, 2025), when a student loan, including one on an income-driven plan, shows a current payment of $0, lenders using Freddie Mac's system count 0.5% of the outstanding balance unless other documentation supports a payment above zero.
That means the same borrower can qualify for more with a Fannie Mae loan than a Freddie Mac loan if their income-driven payment is $0. Lenders can often run both.
What are the FHA student loan guidelines?
For FHA loans, HUD's rule since August 2021 is simple. "Regardless of payment status," the lender uses the payment on your credit report or your actual documented payment when it is above zero, or 0.5% of the outstanding balance when the reported payment is zero. That covers deferred loans too. The rule comes from HUD Mortgagee Letter 2021-13.
FHA's lower credit score minimums can make it a fit for some borrowers, so compare how each program counts your loans. Our guide to FHA vs conventional loans compares them side by side.
How do VA loans count student loans?
VA lenders can leave out a student loan entirely if you provide written evidence that it will stay deferred for at least 12 months past closing. Otherwise, they calculate 5% of the balance divided by 12 and use the greater of that figure or the payment on your credit report.
If your reported payment is lower than that calculation, the lender can use it with a statement from your servicer showing the actual terms, dated within 60 days of closing. The rule was set out in VA Circular 26-17-02 and carried into VA's lender handbook.
Check your eligibility in our guide to VA loan eligibility.
How do USDA loans count student loans?
USDA follows the FHA approach: the reported or documented payment when it is above zero, or 0.5% of the outstanding balance when it is zero, regardless of payment status. Loans paid by someone else still count, and loans in a forgiveness program count until you are released from liability, according to USDA's underwriting handbook.
USDA offers 100% financing in eligible rural areas; see our guide to USDA loans in Virginia and West Virginia.
How much does a student loan reduce what you can afford?
Here is how a $40,000 balance with a $0 income-driven payment would be counted under each program:
| Loan program | Monthly payment counted |
|---|---|
| Fannie Mae (documented $0 income-driven payment) | $0 |
| Freddie Mac | $200 |
| FHA | $200 |
| USDA | $200 |
| VA (not deferred, no servicer statement) | $167 |
Our illustration of each program's formula on a $40,000 balance.
In our estimate (an FHA purchase in Prince George’s County with 3.5% down, a 43% ratio, a 7.32% rate, and property taxes and insurance included), each $100 of monthly debt removes roughly $12,000 of buying power, so a $200 counted payment can cost about $25,000 of price range. To see the full math at one income level, read our guide to how much house you can afford on $60,000.
What do the 2026 student loan changes mean for your mortgage?
Federal student loan repayment changed a lot in 2026. A court order ended the SAVE plan, and the Department of Education's new Repayment Assistance Plan, or RAP, became available on July 1, 2026, with payments based on income and a $10 minimum monthly payment. The ICR and PAYE plans end no later than July 1, 2028. See Federal Student Aid's plan FAQs for your options.
Our reading: because RAP has a $10 minimum, borrowers who move to it will no longer show a $0 payment, so for FHA, USDA and Freddie Mac loans the counted payment could change from 0.5% of the balance to your actual RAP payment, which may be lower or higher. VA still uses the greater of the reported payment or 5% of the balance divided by 12, unless a servicer statement dated within 60 days documents the lower payment. Ask your lender to recheck if your plan changed recently.
Staying current matters more than ever. The CFPB notes that federal loans owned by the Department of Education are reported delinquent at 90 days and most go into default after 270 days, which hurts your credit; see its tips for student loan borrowers. Collections on defaulted loans resumed in May 2025, and the Department delayed involuntary collections such as wage garnishment in January 2026 and, as of October 2026, has not announced an end date.
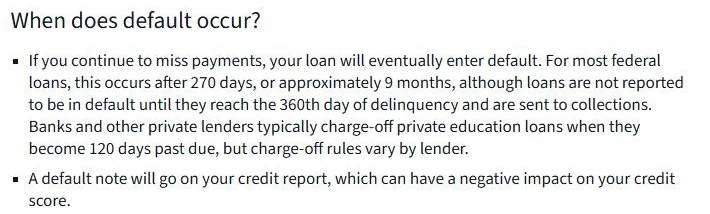
The CFPB explains when student loans default and how that shows up on your credit.
Our guide to the credit score needed to buy a house shows the minimums by loan type.
Is there a program that pays off student loans when you buy?
In Maryland, yes. The Maryland Mortgage Program's SmartBuy 3.0 can pay off student debt at closing, up to 15% of the purchase price subject to a program cap. The full student debt of at least one borrower must be paid off, the help is forgivable over five years, and the program requires a 720 minimum credit score and an approved SmartBuy lender. Our Maryland SmartBuy guide covers the details.
We did not find a comparable statewide student debt payoff program in Virginia or DC, but other first-time buyer help may still apply; see our first-time homebuyer guide.
How can you improve your chances of approval with student loans?
- Pull your credit report and make sure each student loan shows the correct payment
- Get your most recent servicer statement, plus income-driven plan approval letters if your payment is $0
- If a loan is deferred, get written proof of how long, especially for a VA loan
- Ask your lender to compare FHA, Fannie Mae and Freddie Mac treatment of your loans
- Pay off small balances if it lowers your ratio (Fannie Mae already leaves out most installment debts with 10 or fewer payments left)
- Keep every student loan current while you shop and after you apply
Our mortgage documents checklist lists what else to gather.

Get a Mortgage Estimate for Free
See how each loan program would count your student loans and what you can afford.
✓Free, no obligation✓Licensed in VA, MD, DC and WV✓Loan officer Ken Byrne, NMLS #187129
Frequently asked questions
Can I get a mortgage with student loans?
Yes. Lenders count a monthly student loan payment in your debt-to-income ratio, and it is one factor lenders weigh along with your credit, income and assets.
What are the FHA student loan guidelines?
FHA uses the payment on your credit report when it is above $0. If it shows $0, the lender counts 0.5% of the outstanding balance, regardless of payment status.
Does a $0 income-driven payment count as $0?
For Fannie Mae loans, it can with documentation. FHA, USDA and Freddie Mac count 0.5% of the balance, and VA uses 5% of the balance divided by 12 unless a recent servicer statement documents a lower payment.
Do deferred student loans count against me?
Usually yes. Fannie Mae counts 1% of the balance or a fully amortizing payment, FHA and USDA count 0.5%, and VA can exclude loans deferred at least 12 months past closing.
How does the VA count student loans?
The greater of the reported payment or 5% of the balance divided by 12, unless the loan is deferred 12+ months past closing or a recent servicer statement shows a lower payment.
Should I pay off student loans before buying a house?
Not always. Paying down a loan can raise your buying power, but keeping cash for your down payment and closing costs often matters more.
Does the new RAP plan affect my mortgage?
It can. RAP has a $10 minimum payment, so it no longer shows as $0. In our reading, FHA, USDA and Freddie Mac lenders would then count your actual RAP payment instead of 0.5% of the balance, while VA uses the greater of that payment or 5% of the balance divided by 12, unless a recent servicer statement documents the lower payment.
Is there help paying off student loans to buy a home?
In Maryland, SmartBuy 3.0 can pay off student debt at closing for eligible buyers using approved lenders.
This article is general information, not financial advice and not a commitment to lend or an offer of credit. How your student loans are counted depends on your loan program, your lender's overlays and your documentation. Federal student loan plans and rules change; check studentaid.gov or your servicer for your own loans. Mortgage guidelines were checked against Fannie Mae, Freddie Mac, HUD, VA and USDA sources on October 23, 2026. Buying power estimates use Freddie Mac's October 22, 2026 average rate of 7.32%.
Categories
Recent Posts









GET MORE INFORMATION

Broker Associate