
MPDU Program in Montgomery County: How to Buy a Moderately Priced Dwelling Unit
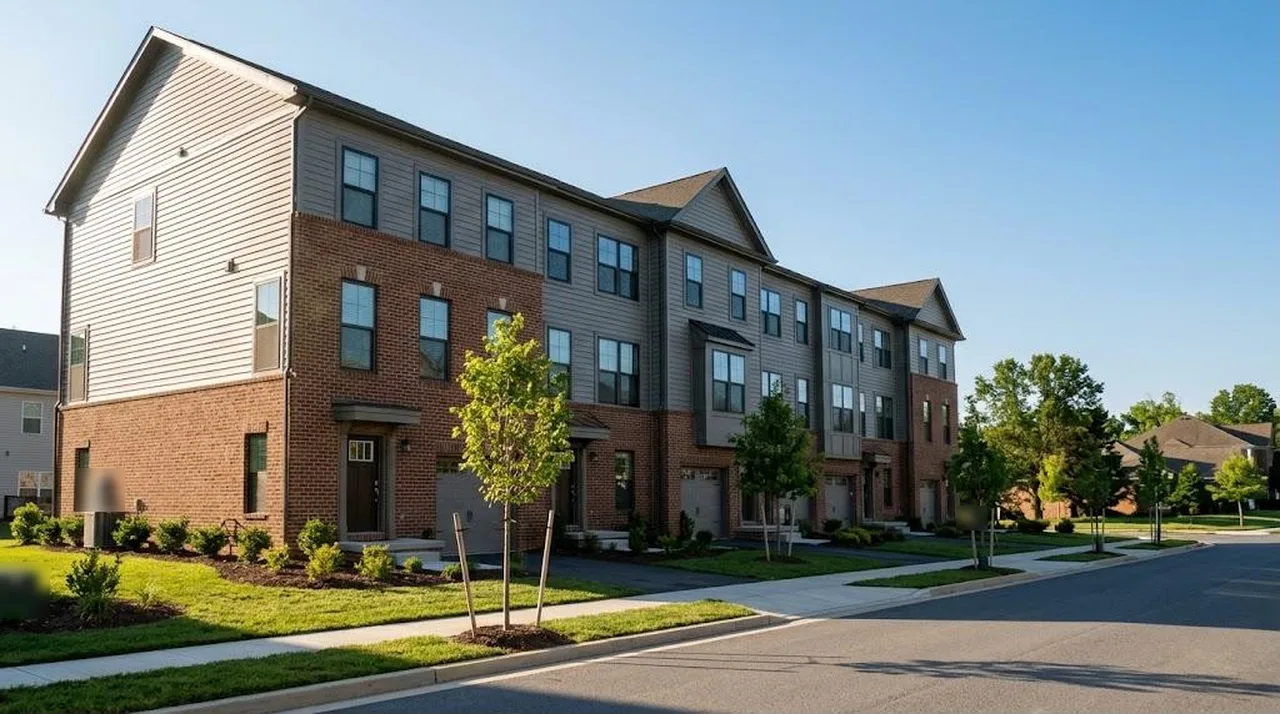
MPDUs are set-aside townhouses and condos, offered new and as resales, at controlled prices to moderate-income first-time buyers.
Short answer: Montgomery County's Moderately Priced Dwelling Unit (MPDU) program sells new and resale homes at controlled prices to first-time buyers with moderate incomes. For 2026, household income must be at least $40,000 and no more than $81,500 for one person or $116,500 for a family of four. You take three free classes, get a certificate of eligibility with a mortgage pre-qualification of at least $150,000, and enter random drawings for available units. In return, the home stays price-controlled for 30 years.
By Ken Byrne, NMLS #187129 · ALCOVA Mortgage LLC, NMLS #40508 · Updated October 2026
In a county where the typical home costs far more than a moderate income can carry, MPDUs are one of the few ways to buy a newer townhouse or condo below market price. This guide explains who qualifies, how the lottery works, what MPDUs cost, how to finance one, and the rules that come with owning one. It covers the County program run by the Department of Housing and Community Affairs (DHCA); Rockville and Gaithersburg run their own programs.
If you are thinking about an MPDU and want a pre-qualification letter you can rely on, JB Financing, the Ken Byrne Team at ALCOVA Mortgage can help you understand what you can borrow.
What is an MPDU?
An MPDU is a home that a developer must set aside and sell or rent at a controlled price under Montgomery County Code Chapter 25A, the Moderately Priced Housing law, which took effect on January 21, 1974. Developments of 20 or more homes must make 12.5% of them MPDUs, or 15% in higher-income planning areas. DHCA certifies buyers, sets prices, runs the drawings and enforces the resale rules. The County's MPDU program page has the background.
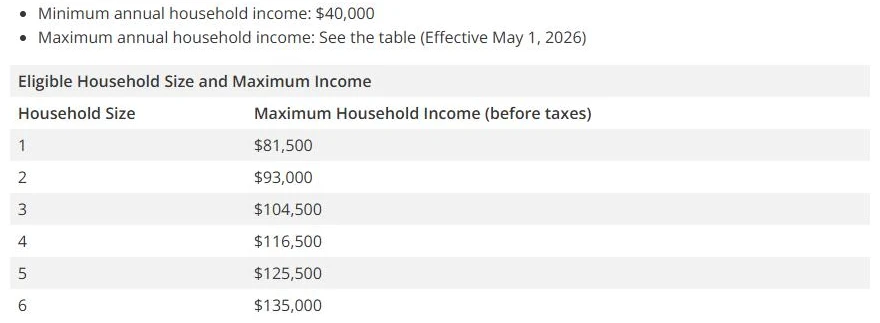
DHCA's MPDU purchase page lists the current income limits.
Who qualifies to buy an MPDU?
| Household size | Maximum household income (before taxes) |
|---|---|
| 1 | $81,500 |
| 2 | $93,000 |
| 3 | $104,500 |
| 4 | $116,500 |
| 5 | $125,500 |
| 6 | $135,000 |
DHCA MPDU Purchase Applicants page, limits effective May 1, 2026. Limits are updated each year, typically in April.
- Minimum income: household income of at least $40,000.
- First-time buyer: no one in the household can currently own a home or have owned one anywhere in the past five years, and no one can ever have owned an MPDU.
- Classes: an MPDU orientation seminar, a first-time homebuyer class and an application tutorial, all free and online.
- Financing: a mortgage pre-qualification letter for at least $150,000.
- Taxes: every adult wage earner must provide a federal tax return for the most recent year.
You do not need to live in Montgomery County to apply, though living or working there earns priority points. The full checklist is on DHCA's MPDU purchase applicants page.
How do you apply for the MPDU program?
Take the three classes in order: the orientation, the 8-hour first-time homebuyer class offered online on the second Saturday of each month, and the application tutorial. Classes count for two years. Then submit your application with your income documents and pre-qualification letter.
Once approved, you receive a certificate of eligibility, which County regulations say expires 12 months after approval; you can apply to renew it within 60 days before it expires. Our guide to pre-qualification vs pre-approval explains what the lender letter shows. Ask DHCA which lenders' letters it accepts, since County regulations call for a letter from a lender approved by the Department.
New to the process? Our first-time homebuyer guide walks through each step from savings to closing.
How does the MPDU lottery work?
When units become available, DHCA posts them on its MPDUs for Sale page with a deadline to enter. The drawing takes place about two to three weeks after a listing is posted. After the entry deadline, eligible entrants are grouped by priority points and randomly ranked within each group. The listing agent then contacts buyers in rank order.
| Priority point | Points |
|---|---|
| Living in Montgomery County | 1 |
| Working in Montgomery County | 1 |
| Each consecutive year as an approved MPDU participant | 1 per year, up to 3 |
| Maximum | 5 |
Your pre-qualification must be at least the unit's price to enter a drawing, and declining a unit does not hurt your future chances. You can sign up for email or text alerts on DHCA's MPDUs for Sale page.
How much does an MPDU cost?
There is no single price list. DHCA sets each development's price with a cost formula based on unit type and size, adjusted each year by the average five-year change in consumer prices, which was 3.86% for 2026. The County's 2026 worksheet example for a 1,450 square foot interior townhouse comes to $226,019.
As a snapshot, for-sale listings shown on DHCA's MPDUs for Sale page in mid-October 2026 required minimum pre-qualified loans of about $220,000 to $245,000 for three-bedroom townhouses. Prices change with each offering, so check current listings. For the typical market price comparison, see our guide to buying with a mortgage in Montgomery County.
What would the monthly payment be on an MPDU?
| $226,019 MPDU, FHA loan | Amount |
|---|---|
| Down payment (3.5%) | $7,911 |
| Loan, with 1.75% upfront premium financed | $221,925 |
| Principal and interest at 7.32% | $1,524/mo |
| FHA mortgage insurance (0.55% a year) | $100/mo |
| Subtotal before taxes, insurance and HOA | $1,624/mo |
Our illustration at Freddie Mac's 30-year average of 7.32% on October 22, 2026, used as an example only. Property taxes, homeowners insurance and any HOA or condo fees add to this.
On a $60,000 household income, an illustrative 43% debt-to-income ratio leaves about $2,150 a month for all debts. Property taxes add at least $147 a month on this price at the County and state base rates alone, before other County levies, insurance and HOA fees, so the full payment can come close to that limit. It is still far easier to fit than a market-rate townhouse. Our guide to how much house you can afford on $60,000 shows the full math.
For Maryland-specific closing costs, including transfer and recordation taxes, see our guide to closing costs in Maryland.
How do you finance an MPDU?
The MPDU program does not provide financing, and DHCA says it does not restrict how an MPDU is financed or how much help a buyer receives from family; your lender may have its own gift rules. You need a regular mortgage. Common choices are FHA, with 3.5% down, and conventional loans with as little as 3% down for eligible buyers; our guide to FHA vs conventional loans compares them. New MPDU condominiums offered by developers must have FHA approval or financing with similar terms.
The Housing Opportunities Commission of Montgomery County's Mortgage Purchase Program can finance MPDUs for first-time buyers with credit scores of at least 640, through its participating lenders.
Down payment help may be available through the Maryland Mortgage Program or the Montgomery Homeownership Program, which the Maryland Mortgage Program runs with the County while funds last, but neither program's published rules say how they work with MPDUs, so confirm with the program and your lender before you count on it. Our guide to the Maryland Mortgage Program covers its general rules.
Your credit score affects both your rate and your mortgage insurance. See our guide to the credit score needed to buy a house.
What rules come with owning an MPDU?
- 30-year control period: for-sale MPDUs stay under price and occupancy controls for 30 years from the original sale, and for units first offered for sale after March 1, 2002, a sale within that period starts a new 30-year control period.
- Owner occupancy: you must live in the home as your primary residence. Renting is allowed only temporarily, with DHCA permission and a rental license, and an unauthorized rental can force a sale.
- Resale price limit: during the control period, you can resell only up to the County-approved price, generally your purchase price plus an inflation allowance and limited credit for improvements and sales costs.
- Refinancing: you cannot refinance for more than the approved resale price, and reverse mortgages are prohibited. Request a resale price determination from DHCA first.
- County first right: the County, through DHCA or the Housing Opportunities Commission, has the right to buy a resale MPDU during the first 60 days after notice.
- Shared profit: at the first sale after the control period ends, the seller pays half of the excess proceeds to the County's Housing Initiative Fund, with an adjustment so the seller keeps at least $10,000.
These rules come from Montgomery County Code Chapter 25A and the County's MPDU regulations; DHCA explains them on its MPDU homeowner page. DHCA also sends owners an annual residency certification.
MPDU pros and cons
| Pros | Cons |
|---|---|
| Newer homes below market price | Limited supply, awarded by lottery |
| Lower loan amount and monthly payment | Resale price capped for 30 years |
| Price set by formula, not bidding wars | Must live in the home; renting needs approval |
| Open to buyers who live or work anywhere | Refinance and cash-out limits |
An MPDU works best for buyers who plan to stay put and value a low payment over fast equity growth. If you want to compare with a market-rate purchase, our guide to how much house you can afford in Maryland is a good starting point.

Get a Mortgage Estimate for Free
Get a pre-qualification letter you can use for MPDU drawings and see what your payment would be.
✓Free, no obligation✓Licensed in VA, MD, DC and WV✓Loan officer Ken Byrne, NMLS #187129
Frequently asked questions
What is an MPDU in Montgomery County?
A Moderately Priced Dwelling Unit: a home developers must set aside and sell at a County-controlled price to moderate-income first-time buyers.
What are the MPDU income limits for 2026?
From $81,500 for one person to $135,000 for six, effective May 1, 2026. Household income must also be at least $40,000.
Do I have to live in Montgomery County to buy an MPDU?
No. Living or working in the County earns priority points in the drawing, but it is not required.
How much is an MPDU?
Prices are set per development. The County's 2026 townhouse example is $226,019, and October 2026 listings needed pre-qualified loans of about $220,000 to $245,000.
Can I sell my MPDU for market value?
Generally not during the 30-year control period. Resale prices are capped, and the first sale after the control period shares half the excess profit with the County.
Can I rent out my MPDU?
Only temporarily, with DHCA permission and a rental license. Owners must otherwise live in the home as their primary residence during the control period.
Can I use an FHA loan for an MPDU?
Yes, FHA is a common choice. New MPDU condominiums offered by developers must have FHA approval or financing with similar terms.
How long is an MPDU certificate good for?
County regulations say 12 months from approval, with renewal allowed starting 60 days before it expires. Classes count for two years.
This article is general information, not legal or financial advice and not a commitment to lend or an offer of credit. The MPDU program is run by Montgomery County's Department of Housing and Community Affairs, which sets and changes its own rules, income limits and prices; Rockville and Gaithersburg run separate programs. Program details were checked against County sources on October 22, 2026. Payment examples are illustrations at Freddie Mac's October 15, 2026 average rate, not quotes.
Categories
Recent Posts









GET MORE INFORMATION

Broker Associate