
How Much House Can I Afford on a $60K Salary in the DMV? County by County
On a $60,000 salary, a condo or townhouse is often the most realistic first home in the DMV.
Short answer: on a $60,000 salary with no other monthly debts, an FHA loan approved through automated underwriting at a 43% ratio supports a home of about $245,000 to $265,000 in most of the DMV, using Freddie Mac's October 22, 2026 average of 7.32%. If FHA's manual underwriting rules apply, the housing payment is generally capped at 31% of income (up to 40% for some borrowers with no other debts), which lowers the range to about $175,000 to $190,000 at 31%. Each $100 of other monthly debt cuts your price by roughly $12,000. Down payment assistance can shrink the cash you bring, and in DC, the HPAP program can add up to $161,600 for one person or $202,000 for two at this income, if funding is available.
By Ken Byrne, NMLS #187129 · ALCOVA Mortgage LLC, NMLS #40508 · Updated October 2026
At $60,000 a year, the typical home in most DMV counties costs more than your income alone can carry, but that does not mean you cannot buy. This guide shows how far $60,000 goes in each part of the region, why automated and manual approvals give very different answers, what the monthly payment looks like, how a second income changes things, and which assistance programs can close the gap.
For numbers based on your own debts, savings and county, talk to the Ken Byrne Team.
How do lenders decide what $60,000 can afford?
Lenders do not use a rule of thumb like three times your salary. They add your monthly housing payment to every other monthly debt and divide by your gross monthly income, which is $5,000 on a $60,000 salary. That debt-to-income ratio, or DTI, has limits that depend on the loan.
| Loan and approval type | Maximum total DTI |
|---|---|
| Conventional, manual underwriting | 36%, up to 45% with strong credit and reserves |
| Conventional, Fannie Mae automated approval (DU) | Up to 50% |
| FHA, manual underwriting | 31% for housing and 43% total; 40/40 with no discretionary debt; up to 37/47 or 40/50 with compensating factors |
| FHA, automated approval | Set by the automated findings, which can approve strong files above 43% |
| VA | 41% guideline; higher with documented compensating factors, especially residual income 20% or more above VA's guideline |
Fannie Mae Selling Guide B3-6-02; HUD Handbook 4000.1; 38 CFR 36.4340.
At 43%, your total monthly debts can be $2,150. At 50%, $2,500. Every dollar of car, student loan or credit card payment comes out of that before the mortgage. The type of approval matters as much as the ratio: with no other debts, a 43% housing payment generally needs an automated FHA approval, because HUD's manual rules limit the housing payment to 31% of income, or 40% if you have no other debts and meet HUD's conditions. Our guide to debt-to-income ratio and mortgage approval explains how lenders count each kind of debt.
How much house can I afford on $60K in each part of the DMV?
Property taxes differ enough across the region to change the answer, so here is the maximum price by area for an FHA loan with 3.5% down under automated and manual approval, plus a VA loan, next to what a typical home there costs.
| Area | Typical home value | FHA, automated approval at 43% | FHA, manual at 31% housing | VA at 41% |
|---|---|---|---|---|
| Washington DC (with homestead deduction) | $566,961 | $266,000 | $190,000 | $259,000 |
| Jefferson County, WV | $400,340 | $262,000 | $185,000 | $255,000 |
| Spotsylvania County, VA | $456,909 | $261,000 | $184,000 | $254,000 |
| Woodbridge, VA | $496,663 | $255,000 | $180,000 | $248,000 |
| Prince George’s County, MD | $421,250 | $251,000 | $177,000 | $244,000 |
| Frederick County, MD | $494,258 | $248,000 | $175,000 | $241,000 |
| Charles County, MD | $442,448 | $247,000 | $174,000 | $240,000 |
| Hagerstown, MD | $300,805 | $230,000 | $163,000 | $223,000 |
Our estimates at 7.32% (Freddie Mac, October 22, 2026), no other debts, homeowners insurance of $115 a month, no HOA dues. FHA: 1.75% upfront premium financed, 0.55% annual premium. VA: 2.15% funding fee financed. Typical values: Zillow Home Value Index, September 2026 (August 2026 for Jefferson County and Hagerstown). Tax rates: 2026 rates; Maryland rates include the state rate of $0.112 per $100; Hagerstown includes the city rate; Woodbridge includes Prince William's fire levy; Jefferson County is outside town limits on West Virginia's 60% assessment; DC is $0.85 per $100 with the $91,950 homestead deduction (tax year 2026 figure).
The pattern is clear: on $60,000 alone, the typical house is out of reach almost everywhere in the region. What fits is a condo, a townhouse or a smaller home in the outer counties, or a bigger budget built with assistance or a second income. Hagerstown comes closest to the typical home, even with the city's higher tax rate. The VA column is lower than FHA here mainly because VA's 41% guideline is below the 43% used for FHA; VA needs no down payment or monthly mortgage insurance, and strong residual income or other compensating factors can let a VA lender go above 41%.
What does the monthly payment look like on $60,000?
Here is the maximum FHA purchase, about $250,806, in Prince George’s County on $60,000 with no other debts.
| $250,806 home, FHA | Amount |
|---|---|
| Down payment (3.5%) | $8,778 |
| Loan, with upfront premium | $246,263 |
| Principal and interest | $1,692/mo |
| FHA mortgage insurance | $111/mo |
| Property tax | $232/mo |
| Homeowners insurance | $115/mo |
| Total monthly payment | $2,150/mo, or 43% of income |
Our estimates at 7.32%. Prince George’s County rate of $1.112 per $100 including the state rate, unincorporated areas; towns add their own rate.
Rates move this more than anything else. At 6.90%, the same budget buys about $260,000; at 7.90%, about $239,000. Freddie Mac's 30-year average was 7.32% on October 22, 2026, down from 7.40% the week before. It is a conventional benchmark; FHA, VA and housing agency rates differ.
How do your debts change what you can afford?
| Other monthly debts | Housing budget at 43% DTI | Housing budget at 50% DTI | Max price, FHA at 43% |
|---|---|---|---|
| None | $2,150 | $2,500 | $251,000 |
| $300 a month | $1,850 | $2,200 | $214,000 |
| $500 a month | $1,650 | $2,000 | $189,000 |
Our estimates on gross monthly income of $5,000; max price for Prince George’s County.
Each $100 of monthly debt removes about $12,000 of buying power at a 7.32% rate. Paying off a small card balance or a car with a few payments left can matter more than saving the same amount toward the down payment. The CFPB's guide on figuring out how much to spend is a useful companion to these numbers.
How does $60K compare with $50K and $75K?
| Salary | Monthly income | Housing budget at 43% | Max price, FHA at 43% | Max price, FHA at 50% |
|---|---|---|---|---|
| $50,000 | $4,167 | $1,792 | $207,000 | $243,000 |
| $60,000 | $5,000 | $2,150 | $251,000 | $294,000 |
| $75,000 | $6,250 | $2,688 | $317,000 | $371,000 |
Our estimates for Prince George’s County with no other debts, on the same terms as above.
Each $10,000 of salary adds roughly $44,000 of price at a 7.32% rate. For the same math one step up, see how much house you can afford on $80,000.
What is $60,000 a year per hour and per paycheck?
Lenders qualify you on gross income, before taxes. $60,000 a year works out to about $28.85 an hour on a 40-hour week, $2,308 per paycheck if you are paid every two weeks, or $5,000 a month. If part of your pay is overtime, bonus or shift pay, lenders generally average it over at least 12 months and often two years, so a recent raise or new overtime may not count in full yet.
How much more can you afford with a second income?
| Household income | Monthly income | Max price, FHA at 43%, Prince George’s County |
|---|---|---|
| $60,000 (one income) | $5,000 | $251,000 |
| $90,000 ($60K + $30,000) | $7,500 | $383,000 |
| $105,000 ($60K + $45,000) | $8,750 | $450,000 |
| $120,000 ($60K + $60,000) | $10,000 | $516,000 |
Our estimates at 7.32%, no other debts, on the same terms as the tables above. Both incomes must be documented, and the co-borrower's debts and credit count too.
A second borrower raises the budget fast, but every borrower's debts and credit are included, and a lower score on either one can set the rate and mortgage insurance for both.
Can you afford a condo or townhouse on $60K?
Many homes in this price range have HOA or condo fees, and lenders count them in the housing payment dollar for dollar.
| Monthly HOA or condo fee | Max price, Prince George’s County | Max price, Washington DC |
|---|---|---|
| $0 | $251,000 | $266,000 |
| $200 | $226,000 | $241,000 |
| $300 | $214,000 | $228,000 |
| $450 | $195,000 | $209,000 |
Our estimates. FHA at 7.32%, 43% DTI, no other debts.
Every $100 of monthly fee takes about $12,000 off your price. A condo also has to be approved by FHA, or the individual unit approved, for an FHA loan, or meet Fannie Mae or Freddie Mac rules for a conventional one, so check the building before you fall for a unit.
Which loans work best on a $60,000 salary?
| Loan | Minimum down payment | Best for |
|---|---|---|
| FHA | 3.5% | Credit in the 600s, or debts that push DTI above conventional limits |
| Conventional | 3% for eligible buyers | Higher credit scores, where mortgage insurance can cost less than FHA's |
| VA | None | Eligible veterans and service members; no monthly mortgage insurance |
| USDA | None | Homes in eligible rural areas, with household income under the county limit |
On $60,000, FHA is often the easiest fit because it allows higher ratios and lower credit scores, but conventional can cost less with strong credit. The side by side is in our guide to FHA vs conventional loans.
Veterans get no down payment and no monthly mortgage insurance, though VA's 41% guideline can mean a slightly lower price limit than FHA unless your residual income or other compensating factors are strong. Check where you stand in our guide to VA loan eligibility.
What down payment help can you get on $60,000?
This is where $60,000 has an edge: it is under the income limits for the main programs in Virginia, Maryland and DC.
| Where you buy | Program | What it gives |
|---|---|---|
| Virginia | Virginia Housing Down Payment Assistance Grant | 2% (conventional) or 2.5% (FHA) of the price, never repaid; first-time buyers, or repeat buyers in Areas of Economic Opportunity, with a Virginia Housing FHA or conventional bond loan; Northern Virginia income limit $148,000 for 1 or 2 people |
| Maryland | Maryland Mortgage Program 1st Time Advantage | $6,000, or 3% to 5% of the loan, as a 0% deferred second loan; 640 minimum credit score; Partner Match can match up to $2,500 of approved partner help, such as employer or local assistance, with the $6,000 option |
| DC | Home Purchase Assistance Program (HPAP) | At $60,000: up to $161,600 for a single buyer or $202,000 for a household of two, plus up to $4,000 for closing costs; deferred until you sell, do a cash-out refinance or move out |
| DC | DC Open Doors | 3% (conventional) or 3.5% (FHA) of the price as a 0% deferred loan; 640 minimum credit score; first-time buyer not required |
Virginia Housing program guidelines and income limits effective August 1, 2026; Maryland Mortgage Program, September 2026; DC DHCD HPAP table for loans closed after July 1, 2026; DC Housing Finance Agency. Checked October 21, 2026.
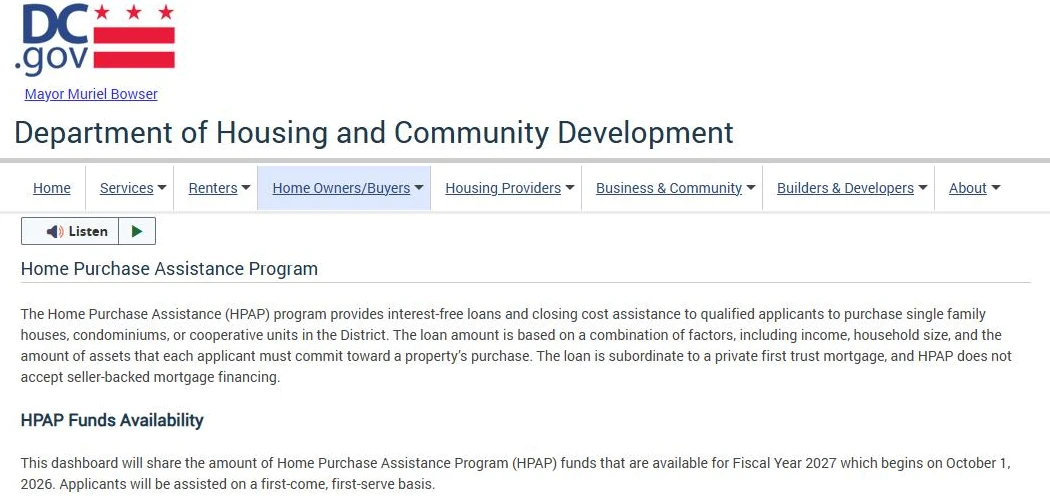
DC's HPAP can add six figures of help at a $60,000 income, while funding lasts.
On a $260,844 FHA purchase in Spotsylvania County, the Virginia Housing grant would pay $6,521 of the $9,130 down payment, so you would bring about $2,608, plus closing costs. Virginia Housing bond loans have their own rates, so your exact price limit may differ. Rules and limits are in our guide to Virginia Housing programs.
In DC, HPAP can change the picture entirely, because that much assistance lifts your price range well beyond the table above. DHCD says assistance for the fiscal year that began October 1, 2026 is first come, first served, so check its funding dashboard before you count on it. Details are in our HPAP guide.
The current income table and application steps are on the DC Department of Housing and Community Development HPAP page.
Maryland buyers can see how the state's programs and taxes change the math in our guide to how much house you can afford in Maryland.
West Virginia buyers in Jefferson and Berkeley counties can also look at the state housing fund's first-time buyer programs, which have their own price limits. See our guide to West Virginia first-time homebuyer programs.
Program terms and credit minimums for Maryland's assistance are on the Maryland Mortgage Program site.
How can you stretch $60,000 further?
| Move | Effect on buying power |
|---|---|
| Pay off a $300 a month debt | About $37,000 more |
| Choose a home with no HOA over one with $300 dues | About $37,000 more |
| Buy with a co-borrower earning $30,000 | About $132,000 more on the same terms |
| Rate 0.5 percentage point lower | About $11,000 more |
| Use a VA loan if eligible | No down payment or monthly mortgage insurance; about $244,000 at a 41% ratio, more with strong residual income |
Our estimates for Prince George’s County on the same terms as the tables above.
A better credit score can also lower your rate and mortgage insurance cost. Our guide to the credit score needed to buy a house shows the minimums by loan type.

Get a Mortgage Estimate for Free
See your real price range on $60,000, with your debts, your county's taxes and the assistance you qualify for.
✓Free, no obligation✓Licensed in VA, MD, DC and WV✓Loan officer Ken Byrne, NMLS #187129
Frequently asked questions
How much house can I afford on $60,000 a year?
About $245,000 to $265,000 in most of the DMV with an automated FHA approval at 43%, or about $175,000 to $190,000 under FHA manual underwriting, assuming no other debts and a 7.32% rate.
What monthly payment can I afford on $60,000?
About $2,150 for all housing costs at a 43% debt-to-income ratio with no other debts, or $2,500 at 50%.
How much house can I afford on $50,000?
About $207,000 in Prince George’s County with an FHA loan and no other debts at 7.32%, or about $243,000 at a 50% ratio.
How much income do I need for a $300,000 house?
About $67,000 to $72,000 a year in most of the DMV, and about $77,000 in Hagerstown, with an FHA loan, no other debts, a 7.32% rate and a 43% ratio.
Can I buy a house in Northern Virginia on $60,000?
Usually a condo or townhouse, or a home farther out such as in Woodbridge; Spotsylvania, in the Fredericksburg area, is another option. Most single-family homes in Fairfax or Loudoun are likely out of reach on $60,000 alone.
Can I buy a home in DC on $60,000?
Possibly, if you are a first-time buyer and HPAP funding is available. HPAP can add up to $161,600 for a single buyer or $202,000 for a household of two at this income.
What credit score do I need?
FHA allows 580 with 3.5% down, though many lenders set higher minimums. The Maryland Mortgage Program and DC Open Doors require 640.
Do I qualify for down payment assistance on $60,000?
Usually, yes. $60,000 is under the income limits for the Virginia Housing grant, the Maryland Mortgage Program and DC's HPAP for most household sizes, if you also meet first-time buyer and other program rules.
This article is general information, not financial advice and not a commitment to lend, an offer of credit or a rate quote. Every figure is an illustration built from published sources and a weekly survey average, not an underwriting decision. Loan limits, program rules, premium schedules, tax rates and rates change, and eligibility depends on a full review of your credit, income, assets and the property. Affordability figures use a 7.32 percent rate from Freddie Mac's survey of October 22, 2026, a conventional benchmark; FHA, VA and housing agency rates differ. They also use county tax rates for 2026 and an assumed insurance cost. Assistance programs are subject to funding and to each program's current limits. Figures were checked on October 23, 2026.
Categories
Recent Posts









GET MORE INFORMATION

Broker Associate