
How Much House Can I Afford on a $100K Salary in Northern Virginia? (2026)
On $100,000 a year, your debts, down payment and rate decide your price range more than the county does.
Short answer: on a $100,000 salary with no other debts and 5% down, you can afford about $277,000 to $290,000 in Northern Virginia under the 28/36 rule, or about $432,000 to $453,000 if your total debts reach 43% of income. That is at a 7.40% rate. Fannie Mae’s automated system can approve some conventional loans up to 50%, or about $500,000 to $523,000.
By Ken Byrne, NMLS #187129 · ALCOVA Mortgage LLC, NMLS #40508 · Updated October 2026
$100,000 is a solid income, but the typical home in most of Northern Virginia costs more than it can carry alone. This guide shows what it buys in eight local jurisdictions, what the monthly payment looks like, and how debts, loan type and rates move the number.
To run the math on your own pay stubs and debts, talk to Ken Byrne at JB Financing.
How much house can I afford with a $100K salary?
Lenders start with gross monthly income. $100,000 a year is $8,333 a month. They then cap your total monthly debts, including the new house payment, at a share of that income called your debt-to-income ratio (DTI).
| Guideline | Share of income | Monthly limit on $8,333 |
|---|---|---|
| 28% housing / 36% total (rule of thumb) | 28% for the house | $2,333 for the house |
| Common planning ceiling | 43% total | $3,583 |
| Fannie Mae manual approval, strong credit and reserves | 45% total | $3,750 |
| Fannie Mae automated approval (maximum) | 50% total | $4,167 |
| VA benchmark | 41% total, plus residual income | $3,417 |
Fannie Mae Selling Guide B3-6-02; 38 CFR 36.4340 for VA. The 28/36 rule and the 43% figure are general planning guidelines, not agency limits. Lenders may set lower limits.
The “house payment” here means principal, interest, property tax, homeowners insurance, mortgage insurance and any HOA dues.
How much house does $100K buy in each Northern Virginia county?
With no other debts, the maximum price is similar everywhere, because only the tax rate changes. Loudoun’s lower rate buys about $21,000 more than the City of Manassas at 43%.
| Area (tax per $100) | 28/36, 5% down | 43%, 5% down | 43%, FHA 3.5% down | 43%, VA 0% down |
|---|---|---|---|---|
| Loudoun ($0.805) | $290,000 | $453,000 | $439,000 | $448,000 |
| Prince William ($0.937) | $286,000 | $446,000 | $433,000 | $442,000 |
| Stafford ($0.9815) | $284,000 | $444,000 | $431,000 | $440,000 |
| Arlington ($1.053) | $282,000 | $441,000 | $428,000 | $437,000 |
| City of Fairfax ($1.0725) | $282,000 | $440,000 | $427,000 | $436,000 |
| Fairfax County ($1.12) | $280,000 | $438,000 | $425,000 | $434,000 |
| Alexandria ($1.135) | $280,000 | $437,000 | $424,000 | $433,000 |
| City of Manassas ($1.24) | $277,000 | $432,000 | $420,000 | $428,000 |
Our estimates. Assumptions: no other debts; 30-year fixed at 7.40%, the Freddie Mac weekly average for October 8, 2026, used for every loan type; homeowners insurance $111 a month (Virginia 2022 average, NAIC); mortgage insurance from one insurer’s published card for a 740 to 759 score; FHA with the 1.75% upfront premium financed and 0.55% annual premium; VA with the 2.15% first-use funding fee financed; no HOA. Tax rates are 2026 locality rates, including the fire levies in Prince William, Manassas and Stafford, before district, town and stormwater add-ons. The VA column uses 43% to match the others; at VA’s 41% benchmark the range is about $408,000 to $427,000.
Every locality’s rate and add-on charges are in our guide to Northern Virginia property tax rates.
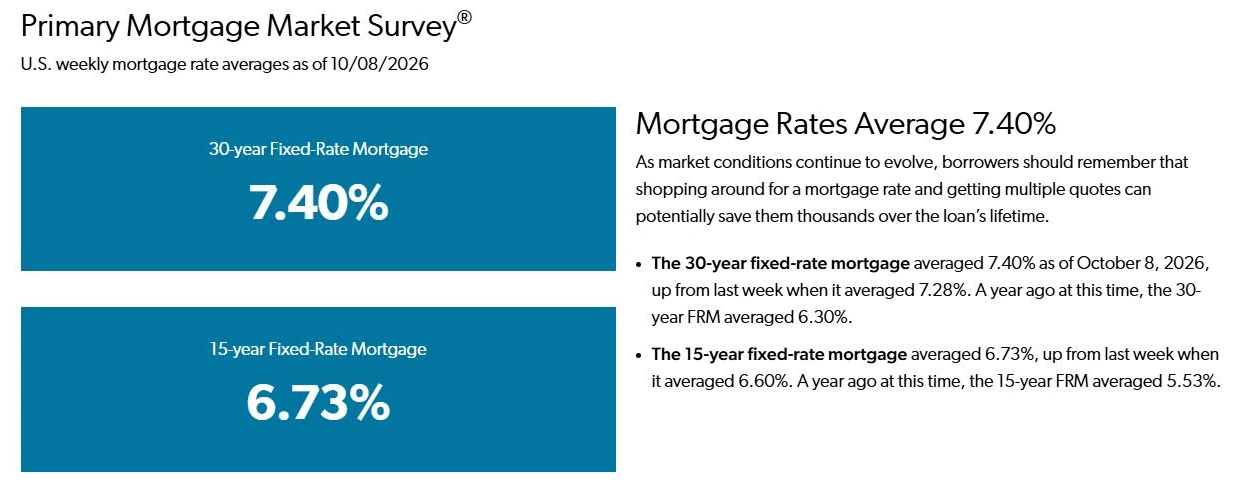
The rate behind every number in this guide. Source: Freddie Mac Primary Mortgage Market Survey, October 8, 2026.
What would the monthly payment be on $100K?
Here is the 43% case in Prince William County with 5% down and no other debts. Figures are rounded to the dollar.
| Item | Amount |
|---|---|
| Purchase price | $446,429 |
| Down payment (5%) | $22,321 |
| Loan amount | $424,107 |
| Principal and interest | $2,936 |
| Mortgage insurance | $187 |
| Property tax ($0.937 per $100) | $349 |
| Homeowners insurance | $111 |
| Total monthly payment | $3,583 (43% of $8,333) |
Under the 28/36 rule, the same buyer in Fairfax County lands at about $280,000: $1,843 principal and interest, $118 mortgage insurance, $262 tax and $111 insurance, or about $2,333 a month after rounding.
On a conventional loan, you can ask to remove mortgage insurance once the balance is scheduled to reach 80% of the original value, and it ends automatically at 78%. FHA annual premiums with less than 10% down last for the life of the loan.
Can you afford a typical Northern Virginia home on $100K?
Not at 43% on one income in any of these eight areas, though the City of Manassas comes close. The table shows the income needed to buy the typical home at 43% with 5% down and no other debts.
| Area | Typical home value | Monthly payment | Income needed at 43% |
|---|---|---|---|
| City of Manassas | $485,835 | $4,013 | About $112,000 |
| Stafford | $537,904 | $4,315 | About $120,000 |
| Prince William | $581,036 | $4,630 | About $129,000 |
| Alexandria | $677,627 | $5,493 | About $153,000 |
| Fairfax County | $760,599 | $6,143 | About $171,000 |
| Loudoun | $795,391 | $6,210 | About $173,000 |
| City of Fairfax | $775,946 | $6,234 | About $174,000 |
| Arlington | $806,890 | $6,465 | About $180,000 |
Typical home values: Zillow Home Value Index, all homes, August 31, 2026. Payments use the assumptions above.
So $100,000 points most buyers toward condos, townhouses and the outer counties, or toward a second income. For the county-by-county view at every income level, see our guide to how much house you can afford in Northern Virginia.
Does FHA, VA or conventional stretch $100K further?
At the same rate, 5% down conventional and VA land close together, and FHA buys a little less because of its upfront and annual premiums.
| $450,000 home | 5% down conventional | FHA 3.5% down | VA 0% down |
|---|---|---|---|
| Fairfax County payment | $3,680 | $3,789 | $3,714 |
| Share of $100K income | 44.2% | 45.5% | 44.6% |
| Prince William payment | $3,611 | $3,721 | $3,645 |
| Share of $100K income | 43.3% | 44.6% | 43.7% |
Same assumptions as above, with one rate for all three loans. In practice FHA and VA rates often differ from conventional rates, which can change the order.
VA also checks residual income, the money left each month after taxes, housing and debts. In Virginia, the minimum for a loan of $80,000 or more is $441 for one person, $738 for two, $889 for three and $1,003 for four.
38 CFR 36.4340, South region. Above 41% DTI, VA expects residual income at least 20% over these amounts to skip extra review.
The trade-offs between the two most common choices are in our comparison of FHA vs conventional loans.
How much do car and student loans cut your budget?
At 43% with 5% down, each $100 of monthly debt removes about $12,500 to $13,000 of buying power. A $500 car payment costs about $62,000 to $65,000 of price.
| Other monthly debt | Fairfax County, 43%, 5% down | Prince William, 43%, 5% down |
|---|---|---|
| $0 | $438,000 | $446,000 |
| $500 | $375,000 | $382,000 |
| $800 | $337,000 | $344,000 |
Deferred student loans usually still count, and FHA counts a payment even when the credit report shows $0. For a $40,000 balance with a $0 payment on the credit report:
| Loan type | Payment lenders count |
|---|---|
| Conventional (Fannie Mae), deferred or in forbearance | 1% of the balance, $400 a month, or the documented full payment |
| Conventional, income-driven plan at $0 | $0, if the lender documents it |
| FHA, $0 reported | 0.5% of the balance, $200 a month |
Fannie Mae Selling Guide B3-6-05; HUD Mortgagee Letter 2021-13.
How lenders weigh each debt is covered in our guide to debt-to-income ratio.
How does your credit score change what $100K buys?
On a conventional loan, a lower score adds an upfront charge from Fannie Mae, which lenders usually pass on in the rate or points. Mortgage insurance also generally costs more with a lower score.
| Credit score | Upfront charge on a $400,000 loan with 3% down |
|---|---|
| 780 or higher | $500 |
| 760 to 779 | $1,000 |
| 740 to 759 | $2,000 |
| 720 to 739 | $3,000 |
| 700 to 719 | $3,500 |
| 680 to 699 | $4,500 |
| 660 to 679 | $5,000 |
| 640 to 659 | $6,000 |
| 639 or lower | $7,000 |
Fannie Mae Loan-Level Price Adjustment Matrix, September 30, 2026, purchase loans over 15 years, above 95% loan-to-value.
First-time buyers with income at or below 100% of the area median, or 120% in high-cost areas, have these charges waived, and many $100K buyers fall under that line. FHA mortgage insurance does not change with your score.
The score each loan needs is in our guide to the credit score you need for a mortgage.
How much do rates change what $100K buys?
At 43% DTI with 5% down, a one point move in rates shifts the maximum price by about $34,000 to $40,000 in Prince William County.
| 30-year rate | Prince William, 43%, 5% down |
|---|---|
| 6.40% | $486,000 |
| 6.90% | $466,000 |
| 7.40% | $446,000 |
| 7.90% | $428,000 |
| 8.40% | $412,000 |
Our estimates, same assumptions, changing only the rate.
Should you borrow the most you qualify for?
Not necessarily. Lenders qualify you on gross pay, but you pay the mortgage from take-home pay after taxes and retirement savings.
A payment at 43% or 50% of gross income can leave little room for repairs, child care or a job change. Keep an emergency fund after closing, and pick a payment you would be comfortable with for years.
A pre-approval shows the lender’s maximum. Your own budget should set the price you actually offer.
Which programs fit a $100K income in Northern Virginia?
At $100,000 you are under several program limits. Each program has its own rules and approved lenders.
| Program | Limit or rule | Does $100K fit? |
|---|---|---|
| Virginia Housing Down Payment Assistance Grant | Income up to $148,000 (1 to 2 people) or $174,000 (3 or more); price up to $800,000; first-time buyers, or repeat buyers in targeted areas; requires a Virginia Housing bond loan | Yes, on income |
| Fannie Mae HomeReady (3% down) | Income at or below 80% of the area median for the address | Likely; the lender checks the address |
| Fannie Mae first-time buyer pricing fee (LLPA) waiver | Income at or below 100% of the area median, or 120% in high-cost areas | Likely, for first-time buyers |
| Loudoun County DPCC | Income $49,850 to $116,299 for any household size; first-time buyers who live or work in Loudoun; up to 10% of price or $70,000, whichever is less | Yes, on income, while funds last |
| Fairfax County Down Payment Loan | Income at or below 80% of area median ($91,750 for one person, $104,900 for two); first-time buyers with a Virginia Housing first mortgage | Yes for households of two or more |
Virginia Housing limits effective August 1, 2026; Fannie Mae Selling Guide B5-6-01 and LLPA Matrix; Loudoun County and Fairfax County program pages, read October 13, 2026.
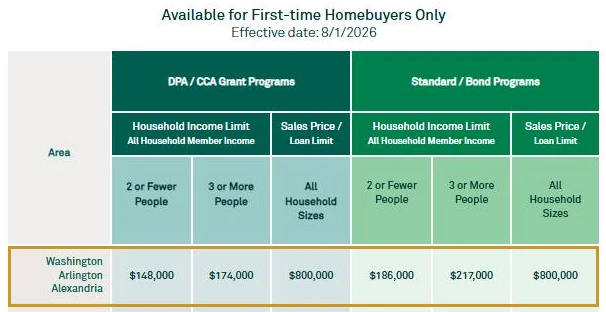
Virginia Housing first-time buyer limits for Northern Virginia, effective August 1, 2026. Source: Virginia Housing.
The grant is 2% with a Conventional Bond loan or 2.5% with an FHA Bond loan, and you put down at least 1%. On a $430,000 home, 2.5% is $10,750. Details are in our guide to Virginia Housing programs.
What other costs should a $100K buyer plan for?
Cash to close includes more than the down payment. Virginia buyers typically pay a state recordation tax of $0.25 per $100 on the deed and again on the loan, plus a local tax of one third of the state tax where the county or city charges it.
On a $430,000 home with 3% down and a $417,000 loan, that is about $2,823 before title, settlement and lender fees. A full list is in our guide to closing costs in Virginia.
HOA and condo dues are part of the housing payment lenders count, so at a 43% limit a $150 HOA lowers your price range by about $19,000, roughly the same as a $150 loan payment.
Earning less? See what an $80K salary buys in the DMV.
On a tighter budget, see how much house you can afford on a $60K salary, with county-by-county estimates.
Earning more? See what a $150K salary buys in the DC area.

Get a Mortgage Estimate for Free
See what $100,000 buys in the county you want, with your real debts and down payment.
✓Free, no obligation✓Licensed in VA, MD, DC and WV✓Loan officer Ken Byrne, NMLS #187129
Frequently asked questions
How much house can I afford with a $100K salary?
About $277,000 to $290,000 in Northern Virginia under the 28/36 rule, or about $432,000 to $453,000 at 43% DTI, with 5% down, no other debts and a 7.40% rate.
What is the monthly income on a $100K salary for a mortgage?
$8,333 a month before taxes. Lenders use gross income, so 43% DTI allows $3,583 for all debts, including the house payment.
Can I afford a $500,000 house on $100K?
Possibly. With 5% down you would need few other debts and a DTI near 50%, which some automated approvals allow. With 20% down, 43% DTI reaches about $528,000 to $559,000.
Can I afford a $400,000 house on $100K?
Often, yes. At 7.40% with 5% down, a 740 to 759 score and no other debts, a $400,000 home costs about $3,178 to $3,323 a month across our eight Northern Virginia areas, or 38% to 40% of gross income. That is under 43% but above the 28/36 guideline.
Is the 28/36 rule realistic in Northern Virginia?
It is a safe target, but at 7.40% with 5% down it limits a $100,000 buyer to about $277,000 to $290,000. Many buyers qualify higher; the question is whether the payment fits your budget.
Is FHA or conventional better on $100K?
With good credit, 5% down conventional often costs less each month than FHA. FHA can help with lower scores or a smaller down payment.
How much does a car payment reduce what I can afford?
At 43% DTI with 5% down, about $12,500 to $13,000 of price for every $100 a month, so a $500 car payment cuts roughly $62,000 to $65,000.
Can I use a VA loan on a $100K salary?
Yes, if you are eligible. With full entitlement, VA usually needs no down payment and has no monthly mortgage insurance, though a one-time funding fee applies unless you are exempt. VA also checks residual income.
Do I qualify for down payment help on $100K?
Often. A Northern Virginia household earning $100,000 is under Virginia Housing’s grant limit. Local programs set their own income limits and have limited funding.
Does a co-borrower change the math?
Yes. Lenders add qualifying income from everyone on the loan. Their debts count too.
This article is general information, not financial or legal advice and not a commitment to lend or an offer of credit. Figures are estimates built on stated assumptions; your rate, taxes, insurance and mortgage insurance will differ. Assistance programs are run by state and local agencies, not by JB Financing or ALCOVA Mortgage. Your eligibility depends on a full review of your credit, income, assets and the property. Rates, tax rates, home values, loan limits and program rules were checked against official sources on October 13, 2026.
Categories
Recent Posts










GET MORE INFORMATION

Broker Associate