
How Much House Can I Afford on a $150K Salary in the DC Area? (2026)
On $150,000 a year, the price ceiling is similar across the DC area. What changes is how much of the local market it reaches.
Short answer: on a $150,000 salary with no other debts and 10% down, you can afford about $453,000 to $477,000 in the DC area under the 28/36 rule, or about $703,000 to $737,000 if your total debts reach 43% of income, at a 7.40% rate. At the 43% level, that covers the typical home in Prince George’s, DC, Montgomery and Alexandria, but not in Fairfax or Arlington; under the 28/36 rule, only Prince George’s typical home fits.
By Ken Byrne, NMLS #187129 · ALCOVA Mortgage LLC, NMLS #40508 · Updated October 2026
$150,000 is above the DC metro median household income of $126,244 (Census, 2024). It goes a long way in some places and not far in others. This guide compares DC, Montgomery County, Prince George’s County, Arlington, Alexandria and Fairfax County, with condo fees, local taxes and the programs a $150,000 earner can still use.
For numbers built on your own income and debts, talk to JB Financing, the Ken Byrne Team at ALCOVA Mortgage.
How much house can I afford with a $150K salary?
$150,000 a year is $12,500 a month before taxes. Lenders compare all your monthly debts, including the new house payment, with that figure.
| Guideline | Share of income | Monthly limit on $12,500 |
|---|---|---|
| 28% housing / 36% total (rule of thumb) | 28% for the house | $3,500 for the house |
| Common planning ceiling | 43% total | $5,375 |
| Fannie Mae manual approval, strong credit and reserves | 45% total | $5,625 |
| Fannie Mae automated approval (maximum) | 50% total | $6,250 |
Fannie Mae Selling Guide B3-6-02. The 28/36 rule is a general guideline, not an agency rule. VA uses 41% as a benchmark and also checks residual income (38 CFR 36.4340).
How much house does $150K buy across the DC area?
With no other debts, the maximum price moves mainly with local property taxes. DC comes out highest because of its low $0.85 rate and its $91,950 homestead deduction, the tax year 2026 amount and the latest the Office of Tax and Revenue has posted.
| Area (tax per $100) | 28/36, 10% down | 43%, 10% down | 43%, 5% down | 43%, FHA 3.5% | 43%, VA 0% |
|---|---|---|---|---|---|
| Washington DC ($0.85) | $477,000 | $737,000 | $691,000 | $670,000 | $684,000 |
| Arlington ($1.053) | $458,000 | $712,000 | $668,000 | $648,000 | $662,000 |
| Prince George’s ($1.112) | $455,000 | $707,000 | $664,000 | $644,000 | $657,000 |
| Fairfax County ($1.12) | $455,000 | $707,000 | $664,000 | $644,000 | $658,000 |
| Alexandria ($1.135) | $454,000 | $705,000 | $663,000 | $643,000 | $656,000 |
| Montgomery ($1.1521) | $453,000 | $703,000 | $661,000 | $641,000 | $655,000 |
Our estimates. Assumptions: no other debts; 30-year fixed at 7.40%, the Freddie Mac weekly average for October 8, 2026, used for every loan type; homeowners insurance at 2022 state averages (DC $1,384, Maryland $1,392, Virginia $1,332 a year, NAIC); mortgage insurance from one insurer’s published card for a 740 to 759 score; FHA with the 1.75% upfront premium financed; VA with the 2.15% funding fee financed; no HOA. Prince George’s rate is for unincorporated areas; Montgomery’s includes typical special district levies.
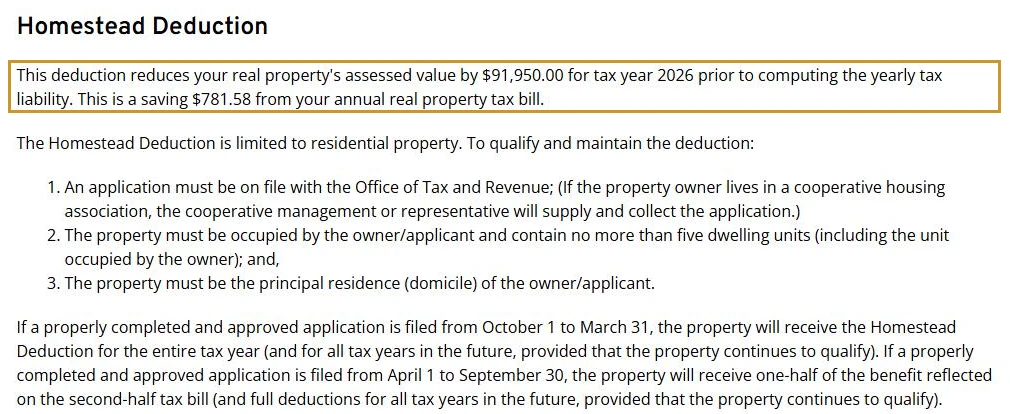
DC’s homestead deduction lowers the taxable value of an owner-occupied home. Source: DC Office of Tax and Revenue.
You must apply for the deduction with the Office of Tax and Revenue; it does not start on its own.
Which DC-area markets fit a $150K budget?
Here is what the typical home costs each month with 10% down, and the share of a $150,000 income it takes.
| Area | Typical home value | Payment, 10% down | Share of $150K | Income needed at 43% |
|---|---|---|---|---|
| Prince George’s | $425,252 | $3,281 | 26.2% | About $92,000 |
| Washington DC | $570,135 | $4,169 | 33.4% | About $116,000 |
| Montgomery | $611,206 | $4,686 | 37.5% | About $131,000 |
| Alexandria | $677,627 | $5,168 | 41.3% | About $144,000 |
| Fairfax County | $760,599 | $5,777 | 46.2% | About $161,000 |
| Arlington | $806,890 | $6,077 | 48.6% | About $170,000 |
Typical home values: Zillow Home Value Index, all homes, August 31, 2026. Payments use the assumptions above.
At 43% with 10% down, $150,000 reaches above the typical home in Prince George’s, DC and Montgomery, and just above it in Alexandria. In Fairfax and Arlington it falls short unless you bring more cash or add income.
Maryland buyers can compare every county in our guide to how much house you can afford in Maryland.
What would a DC condo cost each month on $150K?
Condo fees count as part of your housing payment when lenders figure your DTI. With a $400 monthly condo fee, 5% down and a 45% DTI, the maximum DC condo price is $686,537.
| Item | Amount |
|---|---|
| Purchase price | $686,537 |
| Down payment (5%) | $34,327 |
| Loan amount | $652,211 |
| Principal and interest | $4,516 |
| Mortgage insurance | $288 |
| Property tax (after the homestead deduction) | $421 |
| Condo fee | $400 |
| Total monthly payment, before HO-6 insurance | $5,625 (45% of $12,500) |
The $400 fee alone costs about $52,000 of buying power. Your HO-6 policy for the unit’s interior is extra; each $50 a month of premium lowers the price by about $6,500.
Fannie Mae also charges a 0.75% price adjustment on attached condo loans above 75% loan-to-value, which shows up in the rate or points, although it is waived for first-time buyers who qualify for Fannie Mae’s income-based waiver. Programs and loan options in the city are on our Washington DC home loans page.
What does a Montgomery County single-family payment look like?
At 43% with 10% down and no other debts, a $150,000 buyer can reach about $703,404 in Montgomery County.
| Item | Amount |
|---|---|
| Purchase price | $703,404 |
| Down payment (10%) | $70,340 |
| Loan amount | $633,063 |
| Principal and interest | $4,383 |
| Mortgage insurance | $200 |
| Property tax ($1.1521 per $100) | $675 |
| Homeowners insurance | $116 |
| Total monthly payment | $5,375 (43% of $12,500) |
Each line is rounded to the dollar, so the lines add to $1 less than the total.
Tax rates differ inside incorporated towns, so check the address. Local lending options are covered in our guide to mortgage lenders in Montgomery County.
How much do debts cost you at $150K?
Each $100 of monthly debt removes about $13,000 to $14,000 of buying power at 43% with 10% down.
| Other monthly debt | Washington DC | Montgomery | Arlington |
|---|---|---|---|
| $0 | $737,000 | $703,000 | $712,000 |
| $500 | $668,000 | $637,000 | $644,000 |
| $1,000 | $599,000 | $570,000 | $577,000 |
43% DTI, 10% down, same assumptions as above.
Putting less down also lowers your ceiling, because the loan and mortgage insurance grow. Conventional mortgage insurance can be removed once you pay the loan down far enough, as our guide to PMI costs explains. FHA premiums with less than 10% down generally stay for the life of the loan.
How does your credit score affect a $150K budget?
On a conventional loan, Fannie Mae adds an upfront charge that shrinks as your score rises, with the lowest tier at 780 and above. Lenders usually pass it on in the rate or points.
| Credit score | Upfront charge on a $400,000 loan with 20% down |
|---|---|
| 780 or higher | $1,500 |
| 760 to 779 | $2,500 |
| 740 to 759 | $3,500 |
| 720 to 739 | $5,000 |
| 700 to 719 | $5,500 |
| 680 to 699 | $7,000 |
| 660 to 679 | $7,500 |
| 640 to 659 | $9,000 |
| 639 or lower | $11,000 |
Fannie Mae Loan-Level Price Adjustment Matrix, September 30, 2026, purchase loans over 15 years, 75.01% to 80% loan-to-value. The charge grows with the loan amount.
A first-time buyer earning $150,000 is likely under Fannie Mae’s 120% of area median limit for high-cost areas, which waives these charges. Mortgage insurance also generally costs more with a lower score.
How can you stretch a $150K budget?
| Option | How it helps |
|---|---|
| Pay down a car or card payment | Each $100 a month you remove adds about $13,000 to $14,000 of buying power at 43% with 10% down |
| Use gift money | Fannie Mae allows gifts from relatives and certain close relationships, with a signed gift letter |
| Ask for seller credits | On a home you will live in, Fannie Mae allows seller help up to 3% above 90% loan-to-value, 6% from 75.01% to 90%, and 9% at 75% or less, based on the lower of price or appraised value |
| Buy down the rate | Each discount point costs 1% of the loan amount and lowers the rate; how much varies by lender |
| Add a co-borrower | Lenders count income from everyone on the loan, along with their debts |
Fannie Mae Selling Guide B3-4.3-04 and B3-4.1-02; CFPB on discount points.
Qualifying for a number does not make it comfortable. Lenders use gross pay, so check the payment against your take-home pay and keep an emergency fund after closing.
Which programs can a $150K earner still use?
$150,000 is about 90% of the 2026 HUD median family income for the DC metro, $166,100. That rules out some programs but not all.
| Program | Income limit | Does $150K fit? |
|---|---|---|
| DC Open Doors | $275,400, borrower income only | Yes |
| DC first-time buyer recordation rate (0.725%) | $209,340 for one person; price up to $794,000 | Yes, for first-time DC buyers |
| DC HPAP | $127,900 (1 person) and $146,150 (2 people), the highest limits in the July 2026 table, which come with the smallest award | No for 1 or 2 people; possibly for 3 or more, subject to funding for the new fiscal year |
| Maryland Mortgage Program (Montgomery, Prince George’s) | $199,320 (1 to 2 people), $232,540 (3 or more) | Yes |
| Virginia Housing grant (Northern Virginia) | $148,000 (1 to 2 people), $174,000 (3 or more) | No for 1 or 2 people; for 3 or more, yes on income, first-time buyers only |
| Fannie Mae HomeReady (3% down) | 80% of the area median for the address | Likely over the limit |
| Fannie Mae first-time buyer pricing fee (LLPA) waiver | 120% of the area median in high-cost areas | Likely, for first-time buyers |
DCHFA, DC Office of Tax and Revenue Form ROD 11 (effective October 1, 2026), DC DHCD July 2026 HPAP table, MMP limits effective June 24, 2026, Virginia Housing limits effective August 1, 2026, Fannie Mae LLPA Matrix. Read October 13, 2026. DC government employees may also qualify for DC4ME and EAHP.
DC Open Doors pairs a first mortgage with a 0% deferred loan for the minimum down payment. How it works is in our guide to DC Open Doors.
In Maryland, MMP’s limits sit well above $150,000. Its products are explained in our guide to the Maryland Mortgage Program.
How much cash do you need to close on $150K?
At the 43% maximum price, the down payment ranges from $0 with VA to about $74,000 with 10% down in DC.
| Down payment option | Washington DC at the 43% maximum | Montgomery at the 43% maximum |
|---|---|---|
| VA 0% | $0 | $0 |
| Conventional 3% (first-time buyers) | $19,992 | $19,142 |
| FHA 3.5% | $23,445 | $22,445 |
| Conventional 5% | $34,552 | $33,045 |
| Conventional 10% | $73,702 | $70,340 |
Taxes at settlement matter too. In DC, a first-time buyer who qualifies pays a 0.725% recordation rate instead of 1.45%. On a $686,537 condo, that is about $4,977 instead of $9,955.
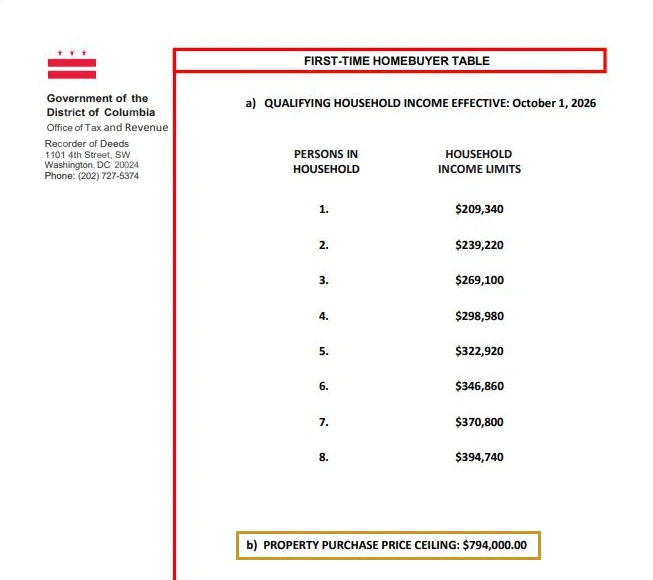
DC’s first-time homebuyer recordation tax limits, effective October 1, 2026. Source: DC Office of Tax and Revenue, Form ROD 11.
In Maryland, the state transfer tax drops to 0.25% for a first-time Maryland buyer and the seller pays it. A line-by-line DC list is in our guide to closing costs in Washington DC.
How much do rates change what $150K buys?
| 30-year rate | Washington DC | Montgomery | Arlington |
|---|---|---|---|
| 6.90% | $769,000 | $733,000 | $742,000 |
| 7.40% | $737,000 | $703,000 | $712,000 |
| 7.90% | $707,000 | $675,000 | $683,000 |
43% DTI, 10% down, no other debts.
A half-point move in the rate shifts the range by about $30,000 at this income. For other income levels, see what $100K buys in Northern Virginia.
Earning more? Our guide to a $200K salary covers high-balance and jumbo loans.
Working with a smaller budget? See how much house you can afford on a $60K salary, with county-by-county estimates for the DMV.

Get a Mortgage Estimate for Free
See what $150,000 buys in DC, Maryland or Northern Virginia, with your real debts and condo fees.
✓Free, no obligation✓Licensed in VA, MD, DC and WV✓Loan officer Ken Byrne, NMLS #187129
Frequently asked questions
How much house can I afford with a $150K salary?
About $453,000 to $477,000 in the DC area under the 28/36 rule, or $703,000 to $737,000 at 43% DTI, with 10% down, no other debts and a 7.40% rate.
What is the monthly income on a $150K salary for a mortgage?
$12,500 a month before taxes. At 43% DTI, that allows $5,375 for all debts, including the house payment.
Can I afford a $700,000 house on $150K?
Only with 10% down and almost no other debt. At 43%, the 10% down ceiling runs from about $703,000 in Montgomery to $737,000 in DC. With 5% down, or a car payment of about $300 a month, $700,000 goes above the 43% line in all six areas.
Is $150K enough to buy in Arlington or Fairfax?
It reaches about $707,000 to $712,000 at 43% with 10% down, below the typical home in both. Lower-priced homes such as some condos and townhouses may fit, but their monthly fees count against your budget.
Why does DC allow a higher price than Maryland or Virginia?
DC’s $0.85 rate and $91,950 homestead deduction mean lower property tax on the same price, so more of your budget goes to the loan.
Do condo fees affect how much I can borrow?
Yes. Lenders count them in your DTI. A $400 monthly fee lowers your maximum price by about $52,000 to $55,000 at this income, depending on your down payment.
Can I get down payment help on $150K?
Some. DC Open Doors and the Maryland Mortgage Program have limits above $150,000. HPAP and Virginia Housing’s grant are out of reach for one- or two-person households at this income.
Is $150K a good salary in the DC area?
It is above the DC metro median household income of $126,244 (Census, 2024) and about 90% of HUD’s 2026 median family income of $166,100. At 43% with 10% down, it buys above the typical home in Prince George’s, DC and Montgomery, and just above it in Alexandria.
Should I put 5% or 10% down?
At 43% DTI, 10% down raises your ceiling by about $46,000 in DC and lowers mortgage insurance. Keep enough cash for closing costs and reserves.
Does a VA loan help at $150K?
Yes, if you are eligible. You need no down payment and no monthly mortgage insurance, and VA checks residual income along with DTI.
This article is general information, not financial or legal advice and not a commitment to lend or an offer of credit. Figures are estimates built on stated assumptions; your rate, taxes, insurance, condo fees and mortgage insurance will differ. Assistance programs and tax benefits are run by government agencies, not by JB Financing or ALCOVA Mortgage. Your eligibility depends on a full review of your credit, income, assets and the property. Rates, tax rates, home values, loan limits and program rules were checked against official sources on October 13, 2026.
Categories
Recent Posts










GET MORE INFORMATION

Broker Associate